Ocean City, MD Real Estate Market Report | October 2026
Last Updated: November 5, 2026. Based on closed Bright MLS sales in the Direct Oceanfront, Oceanfront Indirect View, Ocean Block, Bayside Interior, Bayside Waterfront, and West Ocean City MLS areas, 80 through 85, along with current active, pending, and under-contract inventory as of November 3, 2026.
Jump To Section
- September's Three Questions, Answered
- Quick Answer & Key Takeaways
- How to Read This Report
- October In One Minute
- Grant's Market Minute
- The Story Behind The Statistics
- What Most People Will Miss
- October 2026 Market Snapshot
- What The Numbers Tell Us
- Price Reductions
- Sub-Market Breakdown
- Street Location Breakdown
- Price Range Analysis
- Bedroom Count Analysis
- Notable Sales From October
- Pending Sales & November Outlook
- Cash Buyers
- Who Is Selling Right Now
- What This Means For Buyers
- What This Means For Sellers
- What This Means For Investors
- Frequently Asked Questions
- Three Things I'll Be Watching In November
- Grant's Market Compass
- Market Outlook
- Why You Can Trust This Report
Monthly Letters From the Market: a better way to understand the Ocean City real estate market, with more insight, more context, and more data from local experts.
Every month, the headlines try to summarize the Ocean City real estate market in a sentence or two. They focus on prices, inventory, interest rates, luxury sales, or national housing trends, and they are usually accurate as far as they go. What they rarely answer is the question buyers and sellers actually care about: what does all of this mean for me?
That is the purpose of these reports. The goal is not to publish another pile of MLS statistics, but to interpret what happened, explain why it happened, and help buyers, sellers, investors, and homeowners understand what those changes mean for their next decision. Data without context is just noise, so every report is built around one simple idea: the numbers matter, and understanding them matters even more.
In September We Named Three Things To Watch. October Answered Two Of Them.
The September report ended with three questions for October. The first was whether the price cuts would turn into sales. The second was whether active listings would fall back toward 500 or climb past 600. The third was whether November and December would repeat the strong finish of 2025, with the pipeline at the start of November as the first sign.
The answers came back mixed. The reduced listings that had sat since the spring did sell: 25 October sales had been on the market 91 to 220 days, 21 of them had been reduced, and the typical one closed about 9 percent below its first asking price. But they were not most of the month. More than half of October's sales, 56 of 99, went under contract within 30 days of listing, and only two of those had been reduced. Inventory did neither thing we described: 562 active listings on November 3, 2026, against 559 a month earlier.
The third question has its first answer, and it points to a slower winter. Buyers signed about 86 contracts in October 2026, against 101 in September and 106 in October 2025. That is the fewest of any October in our data, which begins in 2023. October's closings were strong because they came from contracts signed in August and September. November's will come from October's.
Quick Answer: How Is The Ocean City Real Estate Market Performing?
Quick Answer
The Ocean City and West Ocean City real estate market recorded 99 closed sales in October 2026, a preliminary figure, up from 85 in September and close to the 103 of October 2025. The median sale price was $439,900, down 9.3 percent from September's $485,000 and flat against October 2025's $441,000. The more reliable read is the twelve-month median, which was $460,000 for the year ending October 31, 2026, up 3.9 percent over the prior twelve months.
Properties sold faster. The median sale took 28 days to go under contract, the quickest of any month since March 2025, against 59 in September and 44 in October 2025. Active inventory held at 562 listings as of November 3, 2026, about 5.9 months of supply. Price cuts continued on the listing side, and new contracts slowed: about 86 were signed in October, the fewest of any October in our data. That combination describes a market where correctly priced properties still sell quickly while the season turns toward a quieter winter.
Key Takeaways
- October recorded 99 closed sales, preliminary, against 85 in September and 103 in October 2025. Through the first ten months of 2026 the market has recorded 969 sales, 5.9 percent fewer than the 1,030 of the same months of 2025.
- The median sale price was $439,900, down 9.3 percent from September and flat against October 2025. Most of the drop from September is the mix of what sold.
- The twelve-month median through October 31, 2026 was $460,000, up 3.9 percent, and average price per square foot rose 5.5 percent over the same comparison. That is the number to watch, not any single month.
- Median days on market fell to 28, from 59 in September and 44 in October 2025, the quickest since March 2025.
- Active inventory held at 562 listings, about 5.9 months of supply, after 559 on October 5, 2026.
- 122 of the 442 listings that stayed on the market from October 5 to November 3, 2026 cut their asking price, and 276 of 562 active listings, 49 percent, are now priced below their original ask.
- About 86 contracts were signed in October 2026, against 106 in October 2025 and 115 in October 2024.
- Eight sales closed at $1 million or more, after nine in September, and five of the eight buyers paid cash.
- September's preliminary 84 sales finished at 85.
How to Read This Report
October is a month where the closed sales and the contracts point in different directions, and both matter. Three things are worth knowing before drawing conclusions.
First, October's sales count is preliminary, as every month's is when the report is written a few days after month-end. Recent revisions have been small: September finished at 85 against the 84 first reported, because two sales were recorded late and one sale's settlement date was corrected into October. August did not move at all. Earlier in 2026 the revisions were larger, with May rising from 117 to 130, so the comparison against October 2025's 103 should be read with some care.
Second, closed sales and contracts measure different moments. A sale that settled in October usually went under contract in August or September, so October's 99 closings describe the market of late summer. The contracts signed in October, and the price changes on the listings still for sale, describe the market now. This report gives both.
Third, medians and rolling twelve-month figures matter more than one-month averages in a resort market, where a handful of luxury sales or a shift in what sold can move a single month a long way. That is why this report gives weight to the twelve-month median, price per square foot, and days on market rather than treating one headline number as the whole story.
October In One Minute
October was quick at the closing table and quieter at the contract table. More properties settled than in September, and the typical one had found its buyer in four weeks rather than two months. Most of those quick sales were properties that came on the market in late summer and early fall at a price buyers accepted. Prices held: the median was flat against October 2025, and the twelve-month median is up 3.9 percent. On the listing side, owners kept cutting, and nearly half of all active listings are now below their original ask. The signal to watch is the contract count. Buyers signed fewer contracts in October than in any October in our data, which is what the start of a more traditional, slower winter looks like.
Market Minute: What October Felt Like on the Ground
Busy. October was a nice, strong uptick from the previous few months in activity for us, specifically for contracts and closings. It felt like a lot more consumer confidence. The market is still not what it was in the spring, but it was a great month.
"Right now, I wouldn't overreact. Don't panic."
Grant Fritschle
I felt this at the beginning of the year, and I'm even more confident in it right now: Ocean City, and the resort areas around here, are heading back to a more traditional market, the one we got away from in COVID and the post-COVID years. In the more traditional markets, we slow down in the winter, and that's normal.
And to sellers who overreact and start trying to panic and drop their prices: if you're not priced right, yes, go ahead and adjust. But if you believe you are priced right, and the market data tells you you are:
"Adjusting right now is throwing money into a market where there aren't buyers or there aren't many buyers simply because of the time of year."
Grant Fritschle
So don't overreact, don't panic.
The Story Behind The Statistics
The question October raises is whether a fast month with more closings means the fall slowdown is over. The answer, so far, is no, and the reason is in what sold.
October's quick sales were mostly new listings priced to the market. Of the 56 sales that went under contract within 30 days of listing, only two had cut their price first. Those properties came on the market in the late-summer and early-fall listing wave the September report described, when the coming-soon count fell from 32 to 11 and active inventory rose, and buyers took them quickly. The properties that listed high in the spring are a different group. Some of them sold in October after deep reductions, but most are still on the market, and 72 of the 90 active listings that have been listed more than 220 days are now below their original asking price.
Meanwhile the contract count fell. That is the part of October that describes what comes next, and it matches what Grant expects: a market heading back toward the seasonal rhythm it had before 2020, with a slower winter that does not call for panic on either side of the table.
What Most People Will Miss In These Numbers
Most reports will lead with the jump in closed sales, from 85 in September to 99 in October. It is real, but it describes contracts written in August and September, not October.
The contracts signed in October tell the newer story. About 86 were signed in October 2026, against 101 in September and 98 in August, and against 106 in October 2025, 115 in October 2024, and 94 in October 2023. Closings and contracts moved in opposite directions in the same month, and the contracts are the ones that become November's and December's settlements.
The second thing most people will miss is that the median's 9.3 percent drop from September is mostly about what sold. Sales between $600,000 and $799,999 fell from 19 in September to 7 in October, while sales between $400,000 and $599,999 rose from 26 to 42. A month with fewer upper-middle sales produces a lower median without any property losing value. Against October 2025 the median was flat, $439,900 against $441,000, and the twelve-month median is up 3.9 percent.
The third is that fast and firm are not the same thing. The median sale went under contract in 28 days, the quickest since March 2025, but only 22 of 99 sales closed at or above their final asking price, 22 percent, the lowest share since April 2026. Buyers moved quickly on the right properties and still negotiated.
October 2026 Market Snapshot
Here is where the Ocean City and West Ocean City housing market stands at the end of October 2026.
Important Note: September 2026 figures below are revised. The September report called its 84 sales preliminary; the month finished at 85, because two settlements were recorded late and one sale's settlement date was corrected from September 30 to October 1, which moves it into October. October's 99 sales are preliminary and may change as additional settlements are reported. No October sale was excluded for describing more than one property.
| Metric | October 2026 | September 2026 | October 2025 |
|---|---|---|---|
| Units Sold | 99 | 85 | 103 |
| Total Sold Volume | $52,465,281 | $51,062,899 | $52,642,349 |
| Median Sold Price | $439,900 | $485,000 | $441,000 |
| Average Sold Price | $529,952 | $600,740 | $511,091 |
| Avg Price Per Sq Ft | $448 | $454 | $399 |
| Median Days On Market | 28 | 59 | 44 |
| Average Days On Market | 63 | 89 | 85 |
| List-To-Sale Ratio | 96.8% | 97.2% | 96.6% |
| Sold At/Above Asking | 22 (22%) | 25 (29%) | 27 (26%) |
| Sold Below Asking | 77 (78%) | 60 (71%) | 76 (74%) |
| Sales At/Above $1 Million | 8 | 9 | 8 |
Source: Bright MLS, all property types except timeshares. Includes closed sales over $50,000 in the Ocean City and West Ocean City MLS areas, 80 through 85. Asking price is the final asking price before the sale. Medians of an even-numbered set fall on a half day and are rounded up.
Based on information from Bright MLS for the period October 1, 2025 through October 31, 2026.
The Twelve-Month View
Because a single month in a resort market can move a great deal without meaning very much, the more durable measure is the rolling twelve-month figure.
| Rolling Twelve Months | Nov 2025 to Oct 2026 | Nov 2024 to Oct 2025 |
|---|---|---|
| Closed Sales | 1,177 | 1,251 |
| Median Sold Price | $460,000 | $442,690 |
| Avg Price Per Sq Ft | $438 | $415 |
Source: Bright MLS, all property types except timeshares, closed sales over $50,000, MLS areas 80 through 85.
Based on information from Bright MLS for the period November 1, 2024 through October 31, 2026.
Is the Ocean City market up or down? Prices are up, modestly, and activity is down a little. The twelve-month median through October 31, 2026 was $460,000, up 3.9 percent year over year, and price per square foot rose 5.5 percent over the same comparison. The number of sales over the same twelve months fell 5.9 percent. Fewer sales at steadily higher prices is what a market with limited urgency and steady values looks like.
Here's The Simple Version
October was busier at the closing table than September and about even with October 2025. The typical property found its buyer in about four weeks, much faster than in September, because many of the month's sales were new listings priced right. Prices held: the median was flat against a year ago and the twelve-month median kept rising. Owners who priced high in the spring kept cutting. And buyers signed fewer new contracts than in any October in our data, which is the first sign of a slower winter.
What The Numbers Tell Us
Closings Rose, And Contracts Fell
October's 99 closings were the most since August's 102 and close to October 2025's 103. They came from a pipeline built in August and September, when buyers signed about 98 and 101 contracts. The September report expected an October in the range of recent Octobers, 102 in 2024 and 103 in 2025, and the preliminary 99 is just under that range.
The new contracts are lower. About 86 were signed in October 2026. That count includes only contracts still in place or closed by November 3, 2026, so it can still fall slightly if a few pending contracts fail, as September's did: the September report counted about 104, and that figure is now 101.
Properties Sold Faster Than Any Month Since March 2025
Median days on market fell to 28, from 59 in September and 44 in October 2025. It is the quickest monthly median since March 2025. The speed was broad: five of the six sub-markets posted medians of 28 days or less, and Direct Oceanfront led at 15.
We checked the figure a second way, because days on market can reset when a property is relisted. None of October's sales was a relisting under a new MLS number of a property on the market in September or early October, and the seven sales whose days on market looked short against an earlier record had spent that time in coming-soon status, which Bright does not count as days on market.
The Median Fell From September, And The Twelve-Month Median Held
The October median of $439,900 came down from September's $485,000 and was within $1,100 of October 2025's $441,000. The twelve-month median eased to $460,000 from $462,500 through September, while twelve-month price per square foot moved from $434 to $438.
When the monthly median falls this far in a month that sold faster, the mix is the first place to look. October had 42 sales between $400,000 and $599,999 and only 7 between $600,000 and $799,999, against 26 and 19 in September. Three-bedroom properties outsold two-bedrooms, 35 to 34, but at a lower three-bedroom median than September's.
Buyers Paid Asking Less Often
Twenty-two of 99 sales closed at or above asking price, 22 percent, down from 29 percent in September and 26 percent in October 2025, and the lowest share since April 2026. The list-to-sale ratio was 96.8 percent, in the same range it has held all year.
Those two figures are measured against the final asking price, after any reductions. A property that listed at $600,000, cut to $425,000, and sold at $408,000 closed at 96 percent of its final asking price and 68 percent of its original one. The next section measures the cuts themselves.
Price Reductions: What The Listings Are Doing Right Now
Closed sales are a lagging signal. To see what sellers are doing now, we compared two Bright MLS records of every listing in these MLS areas, one pulled October 5, 2026 and one pulled November 3, 2026, and checked each listing's asking price against its price a month earlier and against its original asking price.
Of the 442 listings that were active on both dates, 122 cut their asking price during October, 28 percent, up from 26 percent in September. One raised its price. The typical cut was about 3 percent, and the middle half were between 1.8 and 4.6 percent. By sub-market, West Ocean City had the highest share of listings cutting during the month, 17 of 50, and Oceanfront Indirect View the lowest, 4 of 28.
The cumulative picture kept building. Of the 562 active listings on November 3, 2026, 276, or 49 percent, are now priced below their original asking price, by a typical 4.8 percent, up from 47 percent a month earlier. And the longer a listing has been on the market, the more likely it has been cut:
| Time on market as of November 3, 2026 | Active listings | Now below original ask | Typical cut from original |
|---|---|---|---|
| 30 days or less | 113 | 9 (8%) | 3.0% |
| 31 to 90 days | 193 | 80 (41%) | 3.1% |
| 91 to 220 days | 166 | 115 (69%) | 5.5% |
| More than 220 days | 90 | 72 (80%) | 7.0% |
Source: Bright MLS active listings, all property types except timeshares, MLS areas 80 through 85, as of November 3, 2026. Time on market is days on market as Bright reports it, which can reset when a property is relisted.
Based on information from Bright MLS for the period October 5, 2026 through November 3, 2026.
The table looks much like September's, with one change: the cuts on the oldest listings got deeper. Listings on the market more than 220 days are now a typical 7.0 percent below their original ask, against 6.2 percent a month earlier.
By sub-market, West Ocean City still has the highest share of active listings below their original ask, 38 of 63, followed by Ocean Block at 59 of 114 and Bayside Waterfront at 65 of 131. Bayside Interior and Direct Oceanfront are lowest, at 44 and 45 percent.
The cuts showed up less often at the closing table. Of October's 99 sales, 31 had been reduced before they sold, the lowest share since March 2024, and the typical reduction among those was 5.0 percent, after September's 6.4 percent. That is the other side of October's fast pace: more of the month's sales were properties that never needed a cut.
A note on method: the month-over-month comparison uses the same MLS number in both records. These counts describe asking prices on listings, not what any property is worth.
Ocean City Sub-Market Breakdown
Ocean City is not one single market, and that may be the most important thing to remember when reading any monthly report. Direct oceanfront condos behave differently than bayside waterfront properties, and West Ocean City single-family homes follow a different rhythm than Ocean Block condos.
With 99 recorded sales spread across six sub-markets, five categories carry enough transactions to read as signal this month. One does not, and it is flagged below.
Sales By MLS Location
| Location | Sales | Median Price |
|---|---|---|
| Direct Oceanfront | 20 | $550,000 |
| Oceanfront Indirect View | 5 | $560,000 |
| Ocean Block | 17 | $330,000 |
| Bayside Interior | 25 | $328,000 |
| Bayside Waterfront | 19 | $455,000 |
| West Ocean City | 13 | $455,000 |
Source: Bright MLS, all property types except timeshares, closed sales over $50,000, MLS areas 80 through 85, October 2026.
Based on information from Bright MLS for the period October 1, 2026 through October 31, 2026.
Direct Oceanfront Was Again The Fastest Segment
Direct Oceanfront recorded 20 sales at a $550,000 median and $602 per square foot, again the highest price per square foot in the market. The median oceanfront sale took 15 days, the fastest of any segment for the second month running. Three of the month's eight sales at $1 million or more were here, including the largest, a five-bedroom oceanfront condominium at $2,600,000.
Bayside Interior Led By Count
Bayside Interior recorded 25 sales, the most of any segment, at a $328,000 median and $359 per square foot, still the most accessible segment on the island. The pace improved sharply: a median of 27 days, against 63 in September. Nine of the 25 buyers paid cash.
Bayside Waterfront Lost Its Lead, And Sped Up
After four straight months with the most sales, Bayside Waterfront recorded 19 at a $455,000 median. Its median sale took 28 days, against 103 in September, and its list-to-sale ratio of 98.3 percent was the highest of any segment. None of the month's seven-figure sales was in Bayside Waterfront, after six in September, which is the main reason its median fell from $525,000.
Ocean Block Sold Smaller Units
Ocean Block recorded 17 sales at a $330,000 median, $513 per square foot, and a median of 28 days on market. Its median fell from September's $455,000 because more of its sales were smaller units: eight of the 17 were studios or one-bedrooms, against three of 15 in September. Two of the month's seven-figure sales were also here, a detached house on 140th Street and a three-bedroom condominium at The Meridian.
West Ocean City Picked Up
West Ocean City recorded 13 sales at a $455,000 median and $272 per square foot, with a median of 20 days on market, against six sales and 126 days in September. Its list-to-sale ratio, 94.1 percent, was the lowest of any segment, and it still has the highest share of active listings below their original asking price, 38 of 63. Buyers there are finding properties quickly and negotiating harder than anywhere else.
Read The Small Sample With Caution
Oceanfront Indirect View recorded five sales at a $560,000 median. Two of the five were seven-figure condominiums at Gateway Grand, which lifts the median, and five sales is too few to describe the segment.
Street Location Breakdown
Location remains one of the strongest drivers of long-term value, rental demand, and resale performance in Ocean City real estate. Buyers often focus on the building first, and the building certainly matters, but street location still plays a major role in who a property appeals to, how it rents, how it resells, and how it feels to own.
Sales By Street Range
| Area | Sales | Median Price |
|---|---|---|
| South of 28th Street | 14 | $352,500 |
| 29th to 60th Street | 14 | $425,000 |
| 61st to 90th Street | 18 | $525,000 |
| 91st to 120th Street | 18 | $490,100 |
| 121st Street & North | 22 | $344,000 |
| West Ocean City | 13 | $455,000 |
Source: Bright MLS, all property types except timeshares, closed sales over $50,000, MLS areas 80 through 85, October 2026. Street range is by the cross street recorded in the MLS listing.
Based on information from Bright MLS for the period October 1, 2026 through October 31, 2026.
What This Means
North Ocean City was again the busiest stretch, but less dominant than in September. The 91st Street and north corridors combined for 40 sales, 47 percent of on-island activity, down from 58 percent in September.
The 61st to 90th Street corridor posted the highest median on the island, $525,000, on 18 sales, more than double September's seven. The 121st Street and north corridor posted 22 sales at a $344,000 median, the lowest of any corridor, with half of its sales on the bayside and seven of them studios or one-bedrooms.
The lesson is the same one every month teaches: a median by street range describes what sold, not what things are worth. The 29th to 60th Street corridor had a modest $425,000 median and, on the same 14 sales, the highest average price per square foot on the island, $557. If you are trying to narrow down where to buy, choosing the right condo building deserves as much attention as choosing the corridor.
Price Range Analysis
Inventory is available across the market, but buyer activity is not spread evenly across every price point. Understanding where the sales are happening helps buyers gauge competition and helps sellers understand where their property fits.
| Price Range | October 2026 Sales |
|---|---|
| Under $250K | 12 |
| $250K to $399K | 25 |
| $400K to $599K | 42 |
| $600K to $799K | 7 |
| $800K to $999K | 5 |
| $1M and above | 8 |
Source: Bright MLS, all property types except timeshares, closed sales over $50,000, MLS areas 80 through 85, October 2026.
Based on information from Bright MLS for the period October 1, 2026 through October 31, 2026.
The Story Behind The Numbers
The core of the Ocean City market still lives between $250,000 and $600,000, and in October it held more of the market than at any point this fall. That band accounted for 67 of October's 99 sales, 68 percent, against 47 of 85 in September, 55 percent. The $400,000 to $599,999 band alone had 42 sales, its busiest month since May.
The upper middle thinned out. The three bands above $600,000 accounted for 20 sales, 20 percent of the month, against 30 sales and 35 percent in September, and the $600,000 to $799,999 band fell from 19 sales to 7. The top held: eight sales at $1 million or more. At the entry level, 12 sales closed under $250,000, up from eight, and buyers watching that segment should keep an eye on Ocean City properties under $250,000, where the inventory that does appear tends to move.
Bedroom Count Analysis
Bedroom count continues to shape pricing, demand, marketability, and rental potential across Ocean City and West Ocean City.
| Bedrooms | Sales | Median Price |
|---|---|---|
| Studio | 3 | $190,000 |
| 1 Bedroom | 16 | $270,750 |
| 2 Bedroom | 34 | $428,750 |
| 3 Bedroom | 35 | $530,000 |
| 4+ Bedroom | 11 | $875,000 |
Source: Bright MLS, all property types except timeshares, closed sales over $50,000, MLS areas 80 through 85, October 2026.
Based on information from Bright MLS for the period October 1, 2026 through October 31, 2026.
Key Takeaways
Three-bedroom properties edged out two-bedrooms, 35 sales to 34. The three-bedroom median of $530,000 was well below September's $599,000, and the two-bedroom median of $428,750 was below September's $467,500, which reflects where they sold rather than a change in value. Over the full twelve months, the two-bedroom median is $422,500, up 4.1 percent from $406,000 a year earlier, and the three-bedroom median is $567,500, up 3.2 percent from $550,000. Those are the better numbers for an owner to read as their market.
At the entry level, one-bedroom units recorded 16 sales at a $270,750 median, and three studios closed after none in September. At the top, four-bedroom and larger properties recorded 11 sales at an $875,000 median, against ten at $1,137,500 in September, and four of the 11 were seven-figure sales.
Notable Sales From October
October's notable sales show the same two markets the September report described: properties priced to the market that sold in days, sometimes above asking, and properties that listed high in the spring and sold only after deep reductions.
12201 Wight Street #301, Seaside Plantation, Ocean City: $2,600,000.
5BR | Direct Oceanfront | 35 Days on Market | Closed at 85.2% of asking | Cash.
The largest sale of the month. A five-bedroom oceanfront condominium of about 4,000 square feet, listed at $3,050,000 and sold for cash without a price reduction on the listing.
4001 Atlantic Avenue, Ocean Club, Ocean City: $1,550,000.
4BR | Direct Oceanfront | 0 Days on Market | Closed at 106.9% of asking.
An oceanfront end-unit townhouse that went under contract from coming-soon status, before it counted a day on the active market, and sold for $100,000 over its asking price.
6 140th Street, Ocean City: $1,210,000.
3BR | Ocean Block | 11 Days on Market | Closed at 105.2% of asking | Cash.
A detached house in the Ocean Block area that sold above asking in under two weeks.
5 77th Street #204, Sun Gate I, Ocean City: $575,000.
2BR | Direct Oceanfront | 172 Days on Market | Closed at 96.6% of final asking | Cash.
First listed at $799,000. It sold after nearly six months, at 72 percent of its original asking price.
12 86th Street #2W, Ocean Bali, Ocean City: $408,000.
3BR | Ocean Block | 331 Days on Market | Closed at 96.0% of final asking.
First listed at $600,000 and on the market for almost eleven months, it sold at 68 percent of its original asking price.
404 Saint Louis Avenue #12, Parrot Bay, Ocean City: $265,000.
2BR | Bayside Interior | 156 Days on Market | Closed at 93.3% of final asking.
First listed at $425,000, it sold at 62 percent of its original asking price, the deepest discount from an original ask among October's condominium sales.
Together these sales are the report in six lines. Two properties priced to the market sold in days, above asking. The largest sale was negotiated hard without a reduction on the listing. And the properties that listed well above the market did sell, but after months of waiting and at 28 to 38 percent less than the owners first asked.
Pending Sales & November Outlook
One of the strongest leading indicators in real estate is what is already under contract.
As of November 3, 2026, 117 properties were pending or under contract against 562 active listings, with four more in coming-soon status. The pending count is down slightly from 121 on October 5 and the same as on September 3. The coming-soon count fell again, from 11 to 4, and fewer new listings arrived: about 129 came on the market between October 5 and November 3, 2026, against about 171 a month earlier. Over the same weeks, 50 listings left the market without selling.
The contract count is the clearer signal. About 86 contracts were signed in October 2026, against 101 in September and 106 in October 2025. That count includes only contracts still in place or closed by November 3, 2026, so it may fall slightly if a few of the pending ones fail. Buyers wrote about one in five fewer contracts than they did a year earlier.
That points toward a November with fewer closings than November 2025's 100, and toward the more traditional, slower winter Grant describes in his Market Minute. The honest caveat is that pending counts are a forecast, not a guarantee. A late burst of contracts, or a few more closings than expected, can move a month.
You can always compare against the September 2026 report to see how the trend is developing.
Will Ocean City real estate slow down this winter? The pipeline says it is starting to. About 86 contracts were signed in October 2026, against 106 in October 2025 and 115 in October 2024, and 117 properties were pending or under contract as of November 3, 2026.
Cash Buyers Held Steady, And The Top Went Back To Cash
About 33 percent of October buyers paid cash, 33 of 99, close to September's 34 percent and down from 40 percent in October 2025.
The usual pattern is that cash share rises and falls with the luxury tier, because seven-figure buyers skew toward cash. September broke that pattern, with only two of nine seven-figure buyers paying cash. October went back to it: five of the eight sales at $1 million or more were cash purchases, including the largest. Lower in the market, nine of the 25 Bayside Interior buyers paid cash.
For buyers using financing, the practical guidance has not changed. A strong pre-approval, a lender who understands resort condos and their monthly fees, and a clear view of how a building's finances may affect the loan matter more than ever. Our guide to condo special assessments and the current lending rules covers what changed and when.
What percent of Ocean City buyers pay cash? In October 2026, about 33 percent, close to 34 percent in September. The share has run between 22 and 48 percent over the past twelve months.
Who Is Selling Right Now: A Look At Ownership Tenure
Each month we match every property on the market to Worcester County land records to see how long the seller has owned it. In August and September the same pattern showed up, and in October it held again.
We took every property listed for sale in the Ocean City and West Ocean City MLS areas as of November 3, 2026 and matched it to the county's property records to find the date of the current owner's deed. We then compared those listings against every residential parcel in the 21842 ZIP code, which covers Ocean City and West Ocean City, to see whether some ownership cohorts are listing more often than others.
| Years since current deed | Share of all parcels | Share of listings on market | Listing rate |
|---|---|---|---|
| Under 1 year | 6.7% | 5.2% | 1.3% |
| 1 to 3 years | 13.9% | 16.6% | 2.0% |
| 3 to 5 years | 12.6% | 18.0% | 2.3% |
| 5 to 10 years | 26.2% | 26.6% | 1.7% |
| 10 to 20 years | 20.8% | 18.7% | 1.5% |
| 20 years or more | 19.7% | 14.9% | 1.2% |
Source: Bright MLS active, pending, under-contract, and coming-soon listings, all property types except timeshares, MLS areas 80 through 85, as of November 3, 2026, matched to Worcester County property records published by the Maryland State Department of Assessments and Taxation through Maryland's open data portal, last updated October 6, 2026. 518 of 683 listings matched, 76 percent. The base is 31,387 residential parcels in ZIP code 21842 with a street address and a recorded deed date. Listing rate is the share of each cohort's parcels currently on the market. Overall rate, all cohorts: 1.7 percent.
Based on information from Bright MLS for the period October 1, 2026 through November 3, 2026.
Properties held one to five years are listing at about 2.1 percent of their cohort. Properties held ten years or more are listing at about 1.4 percent. That is the same difference of roughly one and a half times that we reported in August and September. The median property on the market has been held 6.1 years by its current owner, against 7.7 years for the market as a whole.
Broken out by year of purchase, properties deeded in 2022 through 2024 are listing at 2.4 to 2.7 percent, again the highest of any three consecutive purchase years. Properties deeded in 2020 are listing at 1.4 percent, below the market average.
What closed in October looked different from what is listed. Of the October sales we could match, the median seller had held the property 7.0 years, and 34 percent had owned it for less than five years, against 5.9 years and 40 percent in September.
What the table cannot tell you is why any individual owner is selling, and this report does not guess. What it does tell a buyer is that a meaningful share of what is on the market was bought within the last five years, and the last sale price is a matter of public record.
A note on method: the deed date is the last recorded transfer for each parcel, which includes transfers into trusts and between family members as well as arm's-length purchases. Close to half of the deeds recorded in the last five years are transfers of that kind rather than purchases, so a recent deed does not always mean a recent buyer. Counting only purchases, the gap between owners of one to five years and owners of ten years or more is wider, not narrower. The county records were last updated October 6, 2026, so a property that changed hands since then still shows its previous deed. Listings with Berlin mailing addresses in the West Ocean City MLS area fall outside the 21842 ZIP code and are not matched. Parcels without a street address, mostly vacant lots and common areas, are excluded from the base.
What This Means For Buyers Right Now
If you are buying in Ocean City or West Ocean City right now, October gave you two markets to shop in.
The first is the listings priced right. They are selling in days, and in October some of them sold above asking: an oceanfront townhouse at 107 percent of its asking price and a house on 140th Street at 105 percent. On those, a buyer who offers far below the asking price will lose the property to the next buyer.
The second is the listings that have sat. Of the 256 active listings that have been on the market more than 90 days, 187 are already below their original asking price, and the longest-listed are a typical 7 percent below it. Those owners have shown they are ready to talk, and the winter will bring fewer buyers to compete with you.
If I were buying today, I would look first at the listings that have been on the market more than 90 days and have already been reduced, and I would expect to negotiate there. I would look hard at West Ocean City, where the list-to-sale ratio was the lowest of any segment and 60 percent of the active listings are below their original ask. And I would move quickly on anything correctly priced on the oceanfront, because that is where the leverage is thinnest.
Deciding whether the timing is right for you is its own question, and our take on whether buying here makes financial sense is a good place to start.
What This Means For Sellers Right Now
For sellers, October's message is that a correctly priced property still sells quickly, and that the winter is a poor time to chase the market down.
If your property is priced right, the October data is on your side. The median sale took 28 days, the oceanfront took 15, and buyers paid over asking for the right properties. As Grant puts it in his Market Minute, if you believe you are priced right, and the market data tells you that you are, cutting now mostly means giving money to the few buyers who are here at this time of year.
If you listed in the spring and have not had an offer, the data points the other way. Nearly half of all active listings are below their original asking price, the oldest a typical 7 percent below, and buyers comparing your listing with the one next door are looking at a price that has probably already come down. Fewer new contracts were signed in October than in any October in our data, so the pool of buyers is getting smaller, not larger, heading into the winter.
If I were selling today, I would price against October's closed sales in my sub-market and against the reduced prices of my direct competition, not against the original asking prices I see on similar listings. I would expect a slower winter than the fall and plan for it. And if my price was not right, I would adjust once, to the market, rather than in small steps through the winter.
A current valuation, a look at how to prepare a condo for sale, and an honest review of the most common seller mistakes are the right starting points.
What This Means For Investors Right Now
For investors, October is about price discipline and timing.
The twelve-month median is up 3.9 percent and the condominium twelve-month median is up 4.8 percent, so values are still rising slowly. The core $250,000 to $600,000 band held 68 percent of October's sales, its largest share this fall, and that remains the part of the market where rental logic, price, and resale path most reliably line up. With nearly half of active listings below their original ask and fewer buyers writing contracts, an investor buying this winter can set a price based on what the numbers support.
The tenure data adds a practical point. A meaningful share of what is listed was bought between 2022 and 2024, which means the current owner's purchase price is recent, public, and a reasonable anchor for what they hope to net. That is useful information in a negotiation.
If I were evaluating an Ocean City investment property today, I would be less interested in whether October's median fell and more interested in whether the building, location, fee structure, rental demand, and resale path make sense together at a price set by October's closed sales in that sub-market. Financing investors should expect condo documents, fees, special assessments, building financing eligibility, rental rules, occupancy limits, insurance, and realistic income assumptions to matter as much this winter as they did all year.
Frequently Asked Questions
Did The Ocean City Real Estate Market Slow Down In October 2026?
Not at the closing table. Closed sales rose to a preliminary 99 from 85 in September, and the median property went under contract in 28 days, the quickest since March 2025. The slowdown shows in new contracts: about 86 were signed in October 2026, against 106 in October 2025, the fewest of any October in our data, which begins in 2023.
Are Ocean City Sellers Still Cutting Prices?
Yes. Of the 442 listings that were on the market from October 5 to November 3, 2026, 122, about 28 percent, cut their asking price during October, typically by about 3 percent. Of all 562 active listings on November 3, 2026, 276, or 49 percent, were priced below their original asking price. Listings on the market more than 220 days were the most likely to have been reduced, at 80 percent.
Are Ocean City Condo Prices Going Up?
Slowly. Counting only properties recorded in Bright MLS as condominium ownership, the twelve-month median through October 31, 2026 was $440,000 on 766 sales, against $420,000 on 823 sales in the prior twelve months, up 4.8 percent. The October condominium median was $439,900 on 55 sales. Monthly figures move with the mix of what sold; the twelve-month figure is the better guide.
Is Ocean City Currently A Buyer's Market Or Seller's Market?
It is balanced, with buyers holding the edge on listings that have sat. Active inventory stood at 562 listings as of November 3, 2026, about 5.9 months of supply on the trailing three-month sales pace, and 49 percent of active listings are priced below their original ask. Correctly priced properties still sell quickly, though: the median October sale went under contract in 28 days, and Direct Oceanfront sales took a median of 15.
Did September's Sales Figure Change?
Yes, by one sale. The September report called its 84 sales preliminary because Bright MLS settlements are often reported on a lag. Two September settlements were recorded late, and one sale's settlement date was corrected from September 30 to October 1, so September finished at 85, with a median of $485,000 against the $482,500 first reported. October's 99 is preliminary on the same basis.
Which Ocean City Sub-Market Was Strongest In October?
Bayside Interior by volume, with 25 sales at a $328,000 median. Direct Oceanfront by speed and by price per square foot, with a median of 15 days on market and $602 per square foot, and three of the month's eight sales at $1 million or more.
How Long Are Ocean City Properties Taking To Sell?
The median property took 28 days to go under contract in October 2026, down from 59 in September and 44 in October 2025. Five of the six sub-markets had medians of 28 days or less; Oceanfront Indirect View, with five sales, was the exception at 85.
Who Is Selling In Ocean City Right Now?
Disproportionately, the owners of properties deeded within the last five years. Matching current listings to Worcester County property records shows properties held one to five years listing at about 2.1 percent of their cohort, against about 1.4 percent for properties held ten years or more. Properties deeded in 2022 through 2024 are listing at the highest rates of any three consecutive purchase years, 2.4 to 2.7 percent. The median property on the market has been held 6.1 years, against 7.7 years for the market as a whole.
Why Do Your Market Reports Sometimes Differ From National Real Estate Websites?
National websites often rely on broad automated datasets, countywide figures, estimated values, or delayed public records. This report is based on closed Bright MLS sales in specific Ocean City and West Ocean City MLS areas, paired with firsthand interpretation from active local agents. That difference matters because Ocean City is a resort market with many micro-markets that can each behave differently in the same month.
Three Things I'll Be Watching In November
Every monthly report answers one set of questions and creates another. Heading into November, three stand out.
The first is whether October's contract count shows up in November's closings. November 2025 closed 100 sales, November 2024 closed 112, and November 2023 closed 108. If November 2026 comes in well below 100, the slower, more traditional winter Grant expects has arrived. If it holds near 100, October's contract count was a pause, not a turn.
The second is what the owners who listed in the spring do next. There are 90 active listings that have been on the market more than 220 days, and 80 percent of them have already been reduced. In October, 50 listings left the market without selling. If more of the long-listed properties come off the market rather than cut again, the winter inventory will shrink. If they cut again, the share of listings below their original ask will pass half.
The third is inventory. At 562 active listings and fewer new listings arriving, 129 in October against 171 in September, the market is holding near six months of supply. If active listings fall toward 500 by early December, the winter is following the old seasonal pattern. If they hold near 560 while sales slow, months of supply will climb past six and buyers will carry more leverage into the new year.
Grant's Market Compass
A quick read on what strengthened, held steady, and softened in October.
Strengthening: The pace of sales on correctly priced listings, the closed sales count, twelve-month price per square foot, cash participation at the top of the market, and the speed of sales in Bayside Waterfront and West Ocean City.
Holding Steady: The twelve-month median, the condominium twelve-month median, the list-to-sale ratio, active inventory, the seven-figure sales count, and the core price band between $250,000 and $600,000.
Softening: New contracts, the share of sales at or above asking, the monthly median against September, the number of new listings coming on the market, and asking prices on listings that have sat since the spring.
The compass is pointing toward a market entering a normal winter. Values are still rising slowly over twelve months, correctly priced properties still sell fast, and the contract count says the busy part of the fall is behind us.
Market Outlook
Heading into the winter, the Ocean City real estate market is doing what Grant has expected all year: returning to a more traditional, seasonal market, and slowing down without breaking.
The closed sales describe a busy October. The contracts describe a quieter November and December. The listing data describes owners who priced for the spring and are still meeting the fall. All three are true at once, and none of them calls for panic on either side of the table.
What I am reasonably confident about is this: the middle of the market is stable and appreciating slowly, properties priced to the market are selling in weeks, and the owners who listed high in the spring are adjusting. Buyers who find the right property this winter should expect to negotiate on the listings that have sat, and to move quickly on the ones that have not.
What I am not yet confident about is how slow the winter will be. October's contract count is the first sign, not the whole answer. Whether November and December look like the strong finish of 2025 or like the quieter winters this market used to have is the question the next two reports will answer.
Why You Can Trust This Report
Unlike reports that rely solely on automated national datasets, this one combines Bright MLS sales data with active market participation: buyer and seller consultations, showing activity, inventory analysis, contract activity, pricing conversations, and nearly three decades of firsthand Ocean City real estate experience.
It also means being willing to say when the data changed. The September report called its 84 sales preliminary, and the month finished at 85: two settlements were recorded late, and one sale's settlement date was corrected into October. This report says so and uses the corrected figures. October's count is preliminary on the same basis, and the year-over-year comparison should be read accordingly.
The goal is simple: help buyers, sellers, investors, and owners understand what is actually happening in the Ocean City real estate market, without sensational headlines or overly broad national assumptions.
Ocean City is a resort market, a condo market, an investment market, a second-home market, and a lifestyle market all at once, and those layers matter. Reading the numbers correctly requires more than pulling statistics from a database. It requires understanding how buyers think, how sellers respond, how buildings differ, and how individual micro-markets behave from one month to the next.
As Joan Y. put it after selling a property with Grant:
"...He was very responsive to our call(s) and on the first visit was extensively prepared with comparable properties (recently sold and currently on the market). His knowledge of the OCM market, property values, experience and facts helped address our pricing issues."
About The Author
Grant Fritschle is a second-generation Ocean City Realtor and co-founder of The Fritschle Barker Group at Keller Williams Realty of Delmarva. With 29 years of experience and more than 2,000 personal transactions, Grant specializes in oceanfront condominiums, waterfront homes, investment properties, vacation homes, luxury real estate, and resort market analysis. Jon Barker brings more than 20 years of his own experience to the team.
Grant is also co-owner of Central Reservations, one of Ocean City's largest vacation rental management companies, a financial interest disclosed here for transparency, and one that gives him a rare view of both property ownership and rental performance.
Data Source: Bright MLS. Statistics reflect closed sales reported through October 31, 2026 for Ocean City and West Ocean City MLS areas 80 through 85, over $50,000, all property types except timeshares. Sales whose price covers more than one property are excluded from every figure (two in September 2026, none in October). October figures are preliminary and may be revised as additional sales are reported. September 2026 figures are revised from those first published: 85 sales, not 84. Rolling twelve-month figures cover November 1, 2025 through October 31, 2026, compared against November 1, 2024 through October 31, 2025. Inventory, pending, under-contract, and coming-soon counts are as of November 3, 2026. Price changes compare Bright MLS records pulled October 5, 2026 and November 3, 2026. Ownership tenure figures are derived from Worcester County property records published by the Maryland State Department of Assessments and Taxation, last updated October 6, 2026, matched to listings by property address. Based on information from Bright MLS for the period May 1, 2023 through November 3, 2026.
Trust Source Disclosure: This report was researched, written, reviewed, and interpreted by real members of The Fritschle Barker Group. Artificial intelligence tools may be used for editing, formatting, and readability. All market analysis, observations, and opinions reflect local expertise, MLS data, and firsthand experience serving Ocean City and Delaware beach real estate clients.
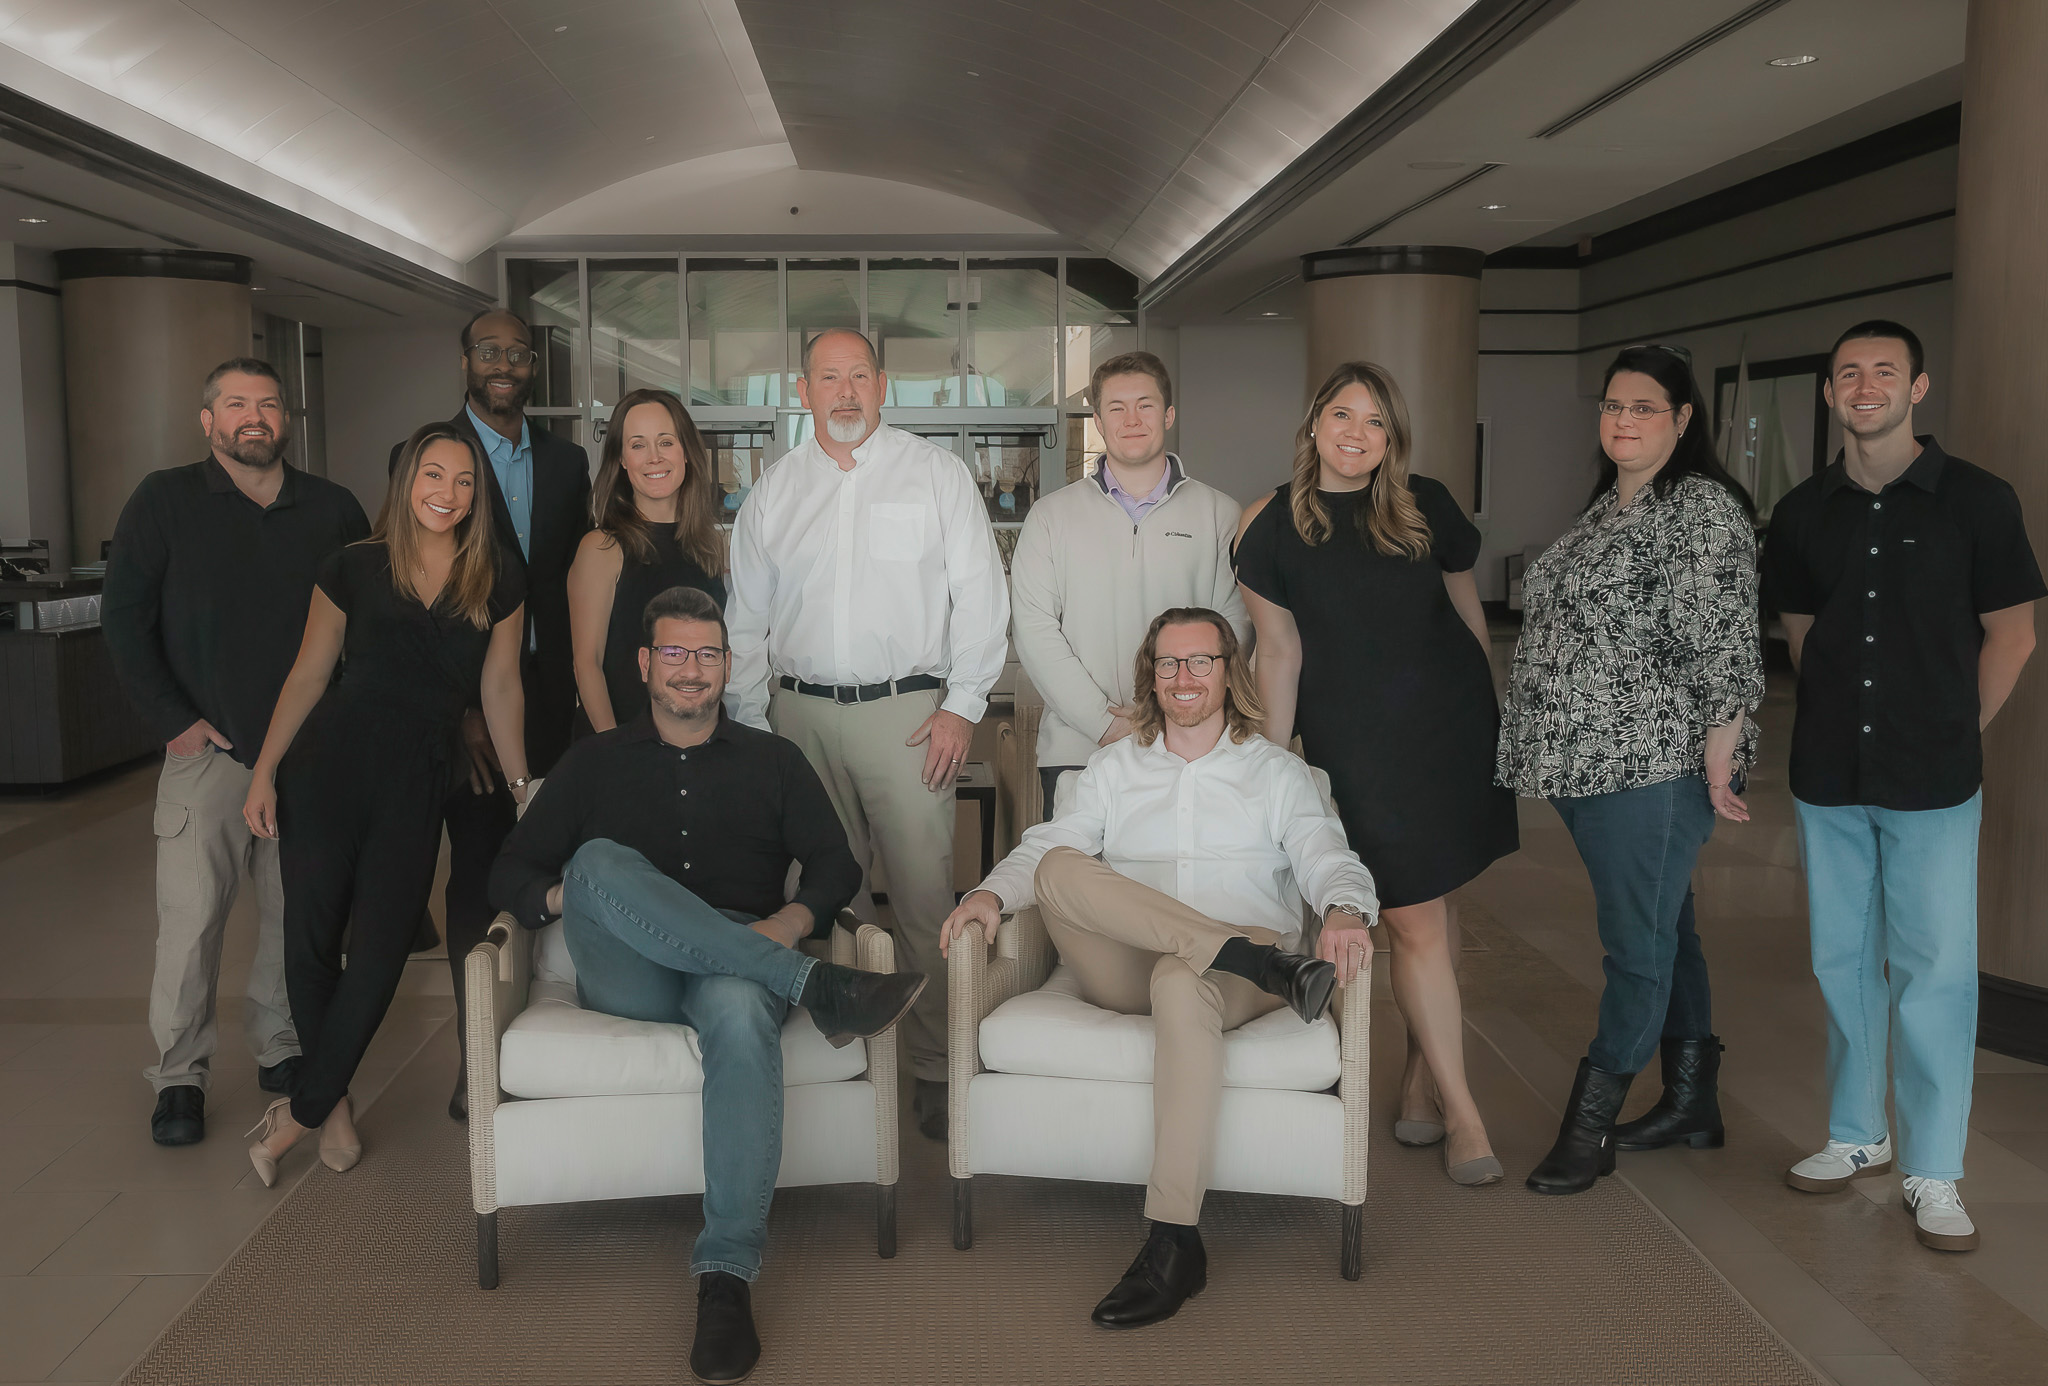
Your Top Ocean City, MD Real Estate Agents
Today, they are recognized nationally as a top-performing group of charismatic, skilled Agents deeply connected to the vibrant towns of the Eastern Shore. More than agents, they are trusted advisors and community advocates, blending local knowledge with national strategy to deliver exceptional results.
The Fritschle Barker Group at Keller Williams Realty of Delmarva adheres to all Fair Housing Act guidelines and NAR ethical standards.