Ocean City, MD Real Estate Market Report | September 2026
Last Updated: October 6, 2026. Based on closed Bright MLS sales in the Direct Oceanfront, Oceanfront Indirect View, Ocean Block, Bayside Interior, Bayside Waterfront, and West Ocean City MLS areas, 80 through 85, along with current active, pending, and under-contract inventory as of October 5, 2026.
Jump To Section
- Quick Answer & Key Takeaways
- How to Read This Report
- September In One Minute
- Grant's Market Minute
- The Story Behind The Statistics
- What Most People Will Miss
- September 2026 Market Snapshot
- What The Numbers Tell Us
- Price Reductions
- Sub-Market Breakdown
- Street Location Breakdown
- Price Range Analysis
- Bedroom Count Analysis
- Notable Sales From September
- Pending Sales & October Outlook
- Cash Buyers
- Who Is Selling Right Now
- What This Means For Buyers
- What This Means For Sellers
- What This Means For Investors
- Frequently Asked Questions
- Three Things I'll Be Watching In October
- Grant's Market Compass
- Market Outlook
- Why You Can Trust This Report
Monthly Letters From the Market: a better way to understand the Ocean City real estate market, with more insight, more context, and more data from local experts.
Every month, the headlines try to summarize the Ocean City real estate market in a sentence or two. They focus on prices, inventory, interest rates, luxury sales, or national housing trends, and they are usually accurate as far as they go. What they rarely answer is the question buyers and sellers actually care about: what does all of this mean for me?
That is the purpose of these reports. The goal is not to publish another pile of MLS statistics, but to interpret what happened, explain why it happened, and help buyers, sellers, investors, and homeowners understand what those changes mean for their next decision. Data without context is just noise, so every report is built around one simple idea: the numbers matter, and understanding them matters even more.
In August We Set A Test For The Fall. September Answered It On The Buyer's Side.
The August report ended with a test. If the fall listings converted to active inventory while the median days on market held under 50, we said, the market was absorbing what it was given. If the active count climbed toward 550 while the median stretched back past 55 days, the fall would favor buyers more than August did.
The second set of conditions is what happened. Active listings stood at 559 on October 5, 2026, up from 511 a month earlier, and the median September sale took 57 days to find its buyer, up from 48 in August. Closed sales fell to 84 from August's 102. The same report expected August's 102 to rise as late settlements came in. None did, and August finished exactly where it was first reported.
None of that describes a market in trouble. The twelve-month median rose to $460,500 through September 30, 2026, up 3.5 percent over the prior twelve months, and the September median of $482,500 was 9.9 percent above September 2025. Nine properties closed at $1 million or more. What changed is the balance between the listings that are priced to the market and the ones that are not. The correctly priced ones still sold quickly, several in two days at or above asking. The ones that listed high in the spring are now cutting their prices, and there are a lot of them.
Quick Answer: How Is The Ocean City Real Estate Market Performing?
Quick Answer
The Ocean City and West Ocean City real estate market recorded 84 closed sales in September 2026, a preliminary figure, down from 102 in August and 120 in September 2025. The median sale price was $482,500, down 5.8 percent from August's $512,000 and up 9.9 percent from September 2025's $439,000. The more reliable read is the twelve-month median, which reached $460,500 for the year ending September 30, 2026, up 3.5 percent over the prior twelve months.
The pace slowed. Median days on market rose to 57, from 48 in August and 37 in September 2025. Active inventory rose to 559 listings as of October 5, 2026, about 6.2 months of supply on the trailing three-month sales pace, up from 4.9 a month earlier. Price reductions picked up: about one in four listings that stayed on the market through September cut its asking price during the month, and nearly half of all active listings are now priced below their original ask. That combination gives buyers a little more leverage than they had in the summer, while correctly priced properties continue to sell quickly.
Key Takeaways
- September recorded 84 closed sales, preliminary, against 102 in August and 120 in September 2025. Through the first nine months of 2026 the market has recorded 869 sales, 6.3 percent fewer than the 927 of the same months of 2025.
- The median sale price was $482,500, down 5.8 percent from August and up 9.9 percent from September 2025.
- The twelve-month median through September 30, 2026 was $460,500, up 3.5 percent, and average price per square foot rose 3.3 percent over the same comparison. That is the number to watch, not any single month.
- Median days on market rose to 57, from 48 in August and 37 in September 2025.
- Active inventory reached 559 listings, about 6.2 months of supply, up from 4.9 months at the start of September.
- New this month: 103 of the 398 listings that stayed on the market from September 3 to October 5, 2026 cut their asking price, and 265 of 559 active listings, 47 percent, are now priced below their original ask.
- Nine sales closed at $1 million or more, after ten in August, six of them in Bayside Waterfront.
- August's preliminary 102 sales finished at 102. It did not revise.
- Properties held one to five years are still listing at about one and a half times the rate of properties held ten years or more.
How to Read This Report
September is a month where the closed sales and the active listings tell different parts of the same story, and both parts matter. Three things are worth knowing before drawing conclusions.
First, September's sales count is preliminary, as every month's is when the report is written a few days after month-end. The last two months suggest the revision will be small: July rose by one sale after its first report, and August did not move at all. Earlier in 2026 the revisions were larger, with May rising from 117 to 130, so the year-over-year comparison against September 2025's 120 should still be read with some care.
Second, this report adds a new measure. We compared the same listings in two Bright MLS records, pulled September 3 and October 5, 2026, to see which ones changed their asking price during September, and we compared every active listing against its original asking price. Closed sales tell you what happened to contracts signed in July and August. The price changes tell you what sellers are doing right now.
Third, medians and rolling twelve-month figures matter more than one-month averages in a resort market, where a handful of luxury sales or a shift in what sold can move a single month a long way. That is why this report gives weight to the twelve-month median, price per square foot, and days on market rather than treating one headline number as the whole story.
September In One Minute
September was slower, and it was supposed to be. Fewer sales closed than in August or September 2025, the typical property took two months to sell, and inventory built up to about six months of supply. At the same time, the twelve-month median kept rising, the oceanfront sold faster than any other part of the market, and the top of the market kept trading, with nine sales at $1 million or more. The clearest new signal is on the listing side: the owners who listed high in the spring are cutting their prices now, at the end of the season, and the properties that have sat longest have cut the most. For buyers, that means more room to negotiate on stale listings. For sellers, it means the market is pricing their competition down around them.
Market Minute: What September Felt Like on the Ground
It is important this month, more than any month so far in 2026, to look past the numbers and at how they got here. September felt like things slowed down, and I think that is because they did. The one thing a lot of people are seeing, and the numbers will show it, is price reductions.
"I'm not ready to hit the panic button on all these price reductions ..."
Grant Fritschle
Here is why. In March, April, May and June, a lot of owners listed without a sense of urgency. They were heading into summer thinking, if it sells, great, and if it doesn't, the rental income is coming in. The market had not slowed or changed yet, so many of them listed high, and a lot of them were reaching. As the market slowly adjusted over the summer, they were not motivated to adjust with it.
Now they are all trying to play catch up. I don't know that prices necessarily dropped, and if they did, maybe just a little. What you are seeing is a lot of owners who reached now adjusting to the market, and they are doing it at the end of the season, when there are fewer buyers here and the market is not as strong. That gives buyers a little bit of leverage right now.
Going into fall and winter, I think we are trending back to the more traditional seasonality this market used to have, with more peaks and valleys. In 2025 we thought the same thing, and then November and December 2025 ended up being very strong months, so we will see if it holds. This time I would not be surprised if the market heads back to what it has traditionally done.
"And winter's going to be a little bit slower, and that's okay. Buyers or sellers shouldn't panic."
Grant Fritschle
I still don't think it is a market where buyers should try overreaching. You want to get your best deal, and you should make that attempt. But if you find the right property, get the best deal you can and buy it. Fair and reasonable wins the day.
The Story Behind The Statistics
The question September raises is whether a slower month with rising inventory is the start of a weaker market or the return of a normal fall. The answer, so far, is the second, with one important qualification about pricing.
When a market genuinely weakens, the long-run measures turn with the monthly ones. The twelve-month median flattens or falls, price per square foot slips, and the correctly priced listings stop selling quickly too. None of that happened in September. The twelve-month median rose to $460,500, price per square foot over twelve months rose to $434, and Direct Oceanfront properties sold in a median of 18 days, the fastest of any segment.
What did happen is that the market sorted itself harder than it had all year. Price and pace are tied together, and in September the listings that were priced right sold in days while the listings that were not sat for months and were cut. Of the active listings that have been on the market more than 90 days, most of them listed in the spring or early summer, about three in four are now below their original asking price. That describes a market working through the gap between what owners hoped for in April and what buyers will pay in October, rather than a market in decline.
What Most People Will Miss In These Numbers
Most reports will lead with the 30 percent drop in sales against September 2025. It is real, but it overstates the change.
September 2025 was an unusually busy September, with 120 sales, against 105 in September 2023 and 73 in September 2024. September 2026's 84 sits between those two earlier years. The better comparison is the year to date: 869 sales through September 2026 against 927 through September 2025, a decline of 6.3 percent. The three summer months, June through August, actually ran slightly ahead of 2025, at 315 sales against 306.
The second thing most people will miss is that the price cuts barely show up in September's closed sales. Only 33 of the 84 sales, about 39 percent, had their price cut before they sold, fewer than in June or July, when more than half had. That is because most of September's closings went under contract in July and August, before the cutting started in earnest. The cuts are on the listings that have not sold yet, and they will show up in closed sales over the next several months, not this one.
The third thing is that the median fell from August while rising 9.9 percent from a year ago, and neither move is mostly about value. September's mix shifted toward two-bedroom oceanfront units and away from the three-bedroom properties that filled August, so the monthly median moved with the mix. The twelve-month median, up 3.5 percent, is the better guide to what a typical Ocean City property did.
September 2026 Market Snapshot
Here is where the Ocean City and West Ocean City housing market stands at the end of September 2026.
Important Note: August 2026 figures below are final and unchanged. The August report called its 102 sales and $63.4 million in volume preliminary and expected late-reported settlements to raise them. None were recorded, and July held at its revised 84 sales. September's 84 sales are preliminary and may rise as additional settlements are reported. Two September sales are excluded from every figure because their price does not describe a single property: a house sold as a package with a separate lot, and three timeshare weeks sold together.
| Metric | September 2026 | August 2026 | September 2025 |
|---|---|---|---|
| Units Sold | 84 | 102 | 120 |
| Total Sold Volume | $50,054,899 | $63,447,826 | $63,593,946 |
| Median Sold Price | $482,500 | $512,000 | $439,000 |
| Average Sold Price | $595,892 | $622,038 | $529,950 |
| Avg Price Per Sq Ft | $456 | $461 | $403 |
| Median Days On Market | 57 | 48 | 37 |
| Average Days On Market | 85 | 90 | 76 |
| List-To-Sale Ratio | 97.3% | 97.0% | 96.8% |
| Sold At/Above Asking | 24 (29%) | 36 (35%) | 31 (26%) |
| Sold Below Asking | 60 (71%) | 66 (65%) | 89 (74%) |
| Sales At/Above $1 Million | 9 | 10 | 7 |
Source: Bright MLS, all property types except timeshares. Includes closed sales over $50,000 in the Ocean City and West Ocean City MLS areas, 80 through 85. Asking price is the final asking price before the sale. Medians of an even-numbered set fall on a half day and are rounded up.
Based on information from Bright MLS for the period September 1, 2025 through September 30, 2026.
The Twelve-Month View
Because a single month in a resort market can move a great deal without meaning very much, the more durable measure is the rolling twelve-month figure.
| Rolling Twelve Months | Oct 2025 to Sep 2026 | Oct 2024 to Sep 2025 |
|---|---|---|
| Closed Sales | 1,180 | 1,250 |
| Median Sold Price | $460,500 | $445,000 |
| Avg Price Per Sq Ft | $434 | $420 |
Source: Bright MLS, all property types except timeshares, closed sales over $50,000, MLS areas 80 through 85.
Based on information from Bright MLS for the period October 1, 2024 through September 30, 2026.
Is the Ocean City market up or down? Prices are up, modestly, and activity is down a little. The twelve-month median through September 30, 2026 was $460,500, up 3.5 percent year over year, and price per square foot rose 3.3 percent over the same comparison. The number of sales over the same twelve months fell 5.6 percent. Fewer sales at steadily higher prices is what a market with limited urgency and steady values looks like.
Here's The Simple Version
September was slower than August and slower than an unusually busy September 2025. The typical property took about two months to sell, and inventory climbed to about six months of supply. Prices held: the twelve-month median kept rising, and the monthly median was well above a year ago. The new development is on the listing side, where owners who priced high in the spring are now cutting their prices. That gives buyers more room on the listings that have sat, while well-priced properties still sell fast.
What The Numbers Tell Us
The Twelve-Month Trend Kept Rising While The Month Slowed
The September median of $482,500 came down from August's $512,000, which was the highest monthly median in our data, and it remains the third highest of 2026, behind August and January. The twelve-month median moved up again, to $460,500 from the $455,000 reported a month ago, and twelve-month price per square foot moved from $430 to $434.
When the monthly median falls and the twelve-month median rises in the same month, the monthly move is about what sold. September had more two-bedroom sales than any other bedroom count, 36 of them, and 13 of those were Direct Oceanfront units, against six in August. A month heavy with oceanfront two-bedrooms and lighter on large three-bedroom homes produces a lower overall median and a higher two-bedroom median at the same time, and that is exactly what September did.
The Pace Slowed, And Inventory Built
Median days on market rose to 57, from 48 in August and 37 in September 2025. It is the clearest sign that September was a slower month on the ground, as Grant describes in his Market Minute.
Inventory moved the same direction. Active listings rose to 559 on October 5, 2026 from 511 on September 3, and the trailing three-month sales pace fell to about 90 a month. That works out to about 6.2 months of supply, up from 4.9 a month ago, or 6.7 months on September's preliminary count alone. Six months is about where many analysts place the upper edge of a balanced market. Ocean City is at that edge now, which is why this report describes buyers as having a little more leverage rather than the upper hand.
The Top Of The Market Kept Trading, With Less Cash
Nine properties closed at $1 million or more in September, after ten in August and seven in September 2025. The August report asked whether August's luxury cluster was a one-month event or the start of a more active fall at the top. Two consecutive months of nine or more seven-figure sales answers the first part of that question.
The September group was different from August's in two ways. It was concentrated, with six of the nine in Bayside Waterfront, and it was mostly financed: two of the nine were cash purchases, against six of ten in August. The largest was a bayside waterfront home at $3,899,900 that sold at its full asking price for cash after 121 days on the market.
Buyers Paid Asking Less Often, But The Ratio Held
Twenty-four of 84 sales closed at or above asking price, 29 percent, down from 35 percent in August and up from 26 percent in September 2025. The list-to-sale ratio was 97.3 percent, in the same range it has held all year.
Those two figures are measured against the final asking price, after any reductions, which is why they look steady even in a month full of price cuts. A seller who listed at $999,900, cut to $850,000, and sold at $750,000 closed at 88 percent of the final asking price and 75 percent of the original. The next section measures the cuts themselves.
Price Reductions: What The Listings Are Doing Right Now
This is a new section, built for this report, and we will run it every month.
Closed sales are a lagging signal. A sale that settles in September usually went under contract in July or August, so it tells you about the market two months ago. To see what sellers are doing now, we compared two Bright MLS records of every listing in these MLS areas, one pulled September 3, 2026 and one pulled October 5, 2026, and checked each listing's asking price against its price a month earlier and against its original asking price.
Of the 398 listings that were active on both dates, 103 cut their asking price during September, about one in four. One raised its price. The typical cut was about 3 percent, and most were between 1.5 and 5 percent. Most of them are modest adjustments.
The cumulative picture is larger. Of the 559 active listings on October 5, 2026, 265, or 47 percent, are now priced below their original asking price, by a typical 4.8 percent. And the longer a listing has been on the market, the more likely it has been cut:
| Time on market as of October 5, 2026 | Active listings | Now below original ask | Typical cut from original |
|---|---|---|---|
| 30 days or less | 140 | 11 (8%) | 3.7% |
| 31 to 90 days | 153 | 56 (37%) | 3.4% |
| 91 to 220 days | 178 | 125 (70%) | 5.1% |
| More than 220 days | 88 | 73 (83%) | 6.2% |
Source: Bright MLS active listings, all property types except timeshares, MLS areas 80 through 85, as of October 5, 2026. Time on market is days on market as Bright reports it, which can reset when a property is relisted.
Based on information from Bright MLS for the period September 3, 2026 through October 5, 2026.
That table is Grant's Market Minute in numbers. The listings that came on the market in the spring and early summer are the ones adjusting now, and seven in ten of them already have. The listings that came on in the 30 days before October 5 mostly have not cut yet, because they have not had to.
By sub-market, West Ocean City has the highest share of active listings below their original ask, 38 of 61, followed by Ocean Block at 58 of 112 and Bayside Waterfront at 65 of 129. Oceanfront Indirect View, Direct Oceanfront, and Bayside Interior are lowest, at about 40 percent each.
The cuts that reached the closing table were deeper than usual. Of September's 84 sales, 33 had been reduced before they sold, and the typical reduction among those was 6.4 percent, the deepest monthly figure in our data, which runs back to April 2023. Fewer of the properties that sold had been cut than in the summer, but the ones that were cut had been cut further. That is what it looks like when the listings that held out longest finally meet the market.
A note on method: the month-over-month comparison uses the same MLS number in both records, and every cut was confirmed against a second field, price per square foot, which moved by the same proportion. These counts describe asking prices on listings, not what any property is worth.
Ocean City Sub-Market Breakdown
Ocean City is not one single market, and that may be the most important thing to remember when reading any monthly report. Direct oceanfront condos behave differently than bayside waterfront properties, and West Ocean City single-family homes follow a different rhythm than Ocean Block condos.
With 84 recorded sales spread across six sub-markets, four categories carry enough transactions to read as signal this month. Two do not, and they are flagged below.
Sales By MLS Location
| Location | Sales | Median Price |
|---|---|---|
| Direct Oceanfront | 16 | $602,500 |
| Oceanfront Indirect View | 1 | $522,000 |
| Ocean Block | 14 | $452,000 |
| Bayside Interior | 22 | $327,500 |
| Bayside Waterfront | 25 | $525,000 |
| West Ocean City | 6 | $500,000 |
Source: Bright MLS, all property types except timeshares, closed sales over $50,000, September 2026.
Based on information from Bright MLS for the period September 1, 2026 through September 30, 2026.
Bayside Waterfront Led For The Fourth Straight Month, Slowly
Bayside Waterfront recorded 25 sales at a $525,000 median, the most of any segment for the fourth consecutive month. It also carried the month's luxury tier, with six of the nine sales at $1 million or more, including the largest sale of the month at $3,899,900.
What changed is the pace. The median Bayside Waterfront sale took 103 days, more than double August's 50 and well above the market figure of 57. This is the segment where the spring's ambitious pricing shows most clearly in what sold: two of the month's deepest discounts from an original asking price were bayside waterfront properties downtown.
Direct Oceanfront Was The Fastest Segment In The Market
Direct Oceanfront recorded 16 sales at a $602,500 median and $577 per square foot, again the highest price per square foot in the market. The median oceanfront sale took just 18 days, the fastest of any segment, and seven of the 16 closed at or above their asking price.
Thirteen of September's 36 two-bedroom sales were oceanfront units, which is the main reason the two-bedroom median rose this month. In a slower month, the oceanfront condominium priced to the market was the property buyers moved on fastest.
Bayside Interior Stayed The Most Accessible Segment On The Island
Bayside Interior recorded 22 sales at a $327,500 median, the most accessible segment in the market by a wide margin, and $386 per square foot. Median days on market was 56, close to the market figure and much improved from August's 104. Ten of the 22 buyers paid cash, the highest cash share of any segment.
Ocean Block Stayed Quick
Ocean Block recorded 14 sales at a $452,000 median, $467 per square foot, and a median of 28 days on market, the same quick pace it held in August. One of the month's seven-figure sales was here, a newer four-bedroom townhouse on 80th Street that sold in two days.
Read The Small Samples With Caution
Oceanfront Indirect View recorded a single sale, at $522,000, and no conclusion should be drawn from one transaction.
West Ocean City recorded six sales at a $500,000 median and $285 per square foot, with a median of 126 days on market. Six sales is too few to describe the segment, but the listing side says more: West Ocean City has the highest share of active listings below their original asking price of any sub-market, 38 of 61. Its larger homes on larger lots take longer to match to a buyer, and this fall more of their owners are adjusting price to do it.
Street Location Breakdown
Location remains one of the strongest drivers of long-term value, rental demand, and resale performance in Ocean City real estate. Buyers often focus on the building first, and the building certainly matters, but street location still plays a major role in who a property appeals to, how it rents, how it resells, and how it feels to own.
Sales By Street Range
| Area | Sales | Median Price |
|---|---|---|
| South of 28th Street | 12 | $505,000 |
| 29th to 60th Street | 14 | $447,500 |
| 61st to 90th Street | 7 | $810,000 |
| 91st to 120th Street | 23 | $510,000 |
| 121st Street & North | 22 | $464,500 |
| West Ocean City | 6 | $500,000 |
Source: Bright MLS, all property types except timeshares, closed sales over $50,000, September 2026. Street range is by the cross street recorded in the MLS listing.
Based on information from Bright MLS for the period September 1, 2026 through September 30, 2026.
What This Means
North Ocean City was again the busiest stretch of the island. The 91st Street and north corridors combined for 45 sales, 58 percent of on-island activity, up from 49 percent in August.
Downtown, south of 28th Street, was busier than usual with 12 sales at a $505,000 median, after five in August. That corridor included two of the month's most heavily negotiated sales, both bayside waterfront properties that sold well below their original asking prices.
The 61st to 90th Street corridor again posted the highest median on the island, $810,000, but on only seven sales, one of them the $1.8 million townhouse on 80th Street. Seven sales is too few to read as a trend.
The lesson is the same one every month teaches: a median by street range describes what sold, not what things are worth. When a corridor's median swings by $100,000 or more on a dozen sales, the mix changed. If you are trying to narrow down where to buy, choosing the right condo building deserves as much attention as choosing the corridor.
Price Range Analysis
Inventory is available across the market, but buyer activity is not spread evenly across every price point. Understanding where the sales are happening helps buyers gauge competition and helps sellers understand where their property fits.
| Price Range | September 2026 Sales |
|---|---|
| Under $250K | 8 |
| $250K to $399K | 22 |
| $400K to $599K | 25 |
| $600K to $799K | 18 |
| $800K to $999K | 2 |
| $1M and above | 9 |
Source: Bright MLS, all property types except timeshares, closed sales over $50,000, September 2026.
Based on information from Bright MLS for the period September 1, 2026 through September 30, 2026.
The Story Behind The Numbers
The core of the Ocean City market still lives between $250,000 and $600,000. That band accounted for 47 of September's 84 sales, about 56 percent, close to August's 57 percent. It is where most of the everyday activity happens: second homes, vacation condos, entry-level beach properties, and investment-friendly units.
The shape of the month held steady even as the count fell. The three bands above $600,000 accounted for 29 sales, 35 percent of the month, about the same share as August. The $800,000 to $999,000 band was the thin spot, with two sales after seven in August. At the entry level, eight sales closed under $250,000, the same as August, and buyers watching that segment should keep an eye on Ocean City properties under $250,000, where the inventory that does appear tends to move.
The count fell at most price levels at once rather than in one segment, and the entry level held steady. That is a more reassuring pattern than a slowdown concentrated at the bottom or the top.
Bedroom Count Analysis
Bedroom count continues to shape pricing, demand, marketability, and rental potential across Ocean City and West Ocean City.
| Bedrooms | Sales | Median Price |
|---|---|---|
| Studio | 0 | n/a |
| 1 Bedroom | 15 | $295,000 |
| 2 Bedroom | 36 | $464,250 |
| 3 Bedroom | 24 | $599,500 |
| 4+ Bedroom | 9 | $1,210,000 |
Source: Bright MLS, all property types except timeshares, closed sales over $50,000, September 2026.
Based on information from Bright MLS for the period September 1, 2026 through September 30, 2026.
Key Takeaways
Two-bedroom properties returned to the top of the market with 36 sales at a $464,250 median, after two months in which three-bedrooms outsold them. The two-bedroom median rose from $405,000 in August, but that reflects where they sold: 13 of the 36 were Direct Oceanfront units. Over the full twelve months, the two-bedroom median is $415,000, up 2.0 percent from $407,000 a year earlier, which is the better number for a two-bedroom owner to read as their market.
Three-bedroom properties recorded 24 sales at a $599,500 median, down from August's 40 sales but at almost the same median as August's $602,500, so the category shrank without getting cheaper.
At the entry level, one-bedroom units recorded 15 sales at a $295,000 median, and no studios closed in September. At the top, four-bedroom and larger properties recorded nine sales at a $1,210,000 median, down from August's $1,502,810 on 12 sales, and seven of the nine were seven-figure sales.
Notable Sales From September
Several September transactions show the two markets running side by side: properties priced to the market that sold in days, and properties that listed high in the spring and sold only after deep reductions.
307 Old Landing Road, Ocean City: $3,899,900.
4BR | Bayside Waterfront | 121 Days on Market | Closed at 100% of asking | Cash.
The largest sale of the month. A newer detached waterfront home of about 3,700 square feet sold at its original asking price for cash after four months on the market. At this level, patience at the right price can be rewarded.
8105 Atlantic Avenue #205, Golden Surf, Ocean City: $810,000.
2BR | Direct Oceanfront | 2 Days on Market | Closed at 101.3% of asking | Cash.
A two-bedroom oceanfront condominium that sold above asking in two days. In a month when the typical property took 57 days, this is what correct pricing on the oceanfront still produces.
13 80th Street #B, Ocean City: $1,800,000.
4BR | Ocean Block | 2 Days on Market | Closed at 97.3% of asking.
A newer four-bedroom townhouse that went under contract in two days, one of the month's nine seven-figure sales.
415 14th Street #55A, Harbour Island, Ocean City: $1,900,000.
6BR | Bayside Waterfront | 494 Days on Market | Closed at 90.5% of final asking.
A large waterfront townhouse of about 4,350 square feet first listed at $2,497,000. It sold after more than sixteen months, at 76 percent of its original asking price.
12704 West End Court, West Ocean City: $1,875,000.
5BR | West Ocean City | 121 Days on Market | Closed at 93.8% of final asking.
First listed at $2,399,999 and reduced to $1,999,000 before it sold, at 78 percent of its original asking price.
310 13th Street #302, Aronimink, Ocean City: $750,000.
3BR | Bayside Waterfront | 113 Days on Market | Closed at 88.2% of final asking | Cash.
A three-bedroom bayside condominium first listed at $999,900, reduced to $850,000, and sold at $750,000, 75 percent of its original asking price.
Together these sales are the whole report in six lines. The properties priced to the market at the start sold in days or sold at full price. The properties that listed well above it in the spring did sell, but after months of waiting and at a quarter less than the owners first asked.
Pending Sales & October Outlook
One of the strongest leading indicators in real estate is what is already under contract.
As of October 5, 2026, 121 properties were pending or under contract against 559 active listings, with 11 more in coming-soon status. The pending count is up slightly from 117 on September 3, 2026. The coming-soon count fell from 32 to 11, which is what the August report expected: the fall listing wave arrived and became active inventory.
Contract activity held up better than closings did. About 104 contracts were signed in September 2026, close to the 101 of August and the 109 of September 2025. That count includes only contracts still in place or closed by October 5, so it may fall slightly if a few of the pending ones fail. Buyers did not disappear in September. They wrote about as many contracts as a year ago, and they were choosier about which listings they wrote them on.
That points toward an October with a closed count in the range of recent Octobers, which ran 102 in 2024 and 103 in 2025, and a buyer pool with more choice than it has had since the spring. The honest caveat is that pending counts are a forecast, not a guarantee. Contracts fall through, financing gets complicated, and inspections change minds.
You can always compare against the August 2026 report to see how the trend is developing.
Will October be busy in Ocean City? The pipeline suggests a normal fall. As of October 5, 2026, 121 properties were pending or under contract against 559 active listings, and about 104 contracts were signed during September, close to September 2025's 109.
Cash Buyers Held Steady While The Top Went Financed
About 35 percent of September buyers paid cash, 29 of 84, down from 39 percent in August and close to the 34 percent of September 2025.
The usual pattern in Ocean City is that cash share rises and falls with the luxury tier, because seven-figure buyers skew toward cash. September broke that pattern. Nine seven-figure sales closed, and only two of them were cash. The cash in September came from the other end of the market instead: ten of the 22 Bayside Interior buyers, the most accessible segment, paid cash.
That matters because it changes who a seller is likely to be negotiating with. At the top of the market this fall, a seller should expect financed buyers with appraisal and lender timelines. In the more affordable segments, cash buyers remain a large share of the pool and can move quickly on a correctly priced unit.
For buyers using financing, the practical guidance has not changed. A strong pre-approval, a lender who understands resort condos and their monthly fees, and a clear view of how a building's finances may affect the loan matter more than ever. Our guide to condo special assessments and the current lending rules covers what changed and when.
What percent of Ocean City buyers pay cash? In September 2026, about 35 percent, down from 39 percent in August. The share has run between 22 and 48 percent over the past twelve months.
Who Is Selling Right Now: A Look At Ownership Tenure
In August we began matching every property on the market to Worcester County land records to see how long the seller had owned it. We said we would run the table every month, because whether a pattern holds is only answerable with repetition. In September it held.
We took every property listed for sale in the Ocean City and West Ocean City MLS areas as of October 5, 2026 and matched it to the county's property records to find the date of the current owner's deed. We then compared those listings against every residential parcel in the 21842 ZIP code, which covers Ocean City and West Ocean City, to see whether some ownership cohorts are listing more often than others.
| Years since current deed | Share of all parcels | Share of listings on market | Listing rate |
|---|---|---|---|
| Under 1 year | 6.6% | 5.4% | 1.3% |
| 1 to 3 years | 14.0% | 15.3% | 1.8% |
| 3 to 5 years | 12.9% | 18.2% | 2.3% |
| 5 to 10 years | 26.0% | 26.2% | 1.7% |
| 10 to 20 years | 20.8% | 19.6% | 1.5% |
| 20 years or more | 19.8% | 15.3% | 1.3% |
Source: Bright MLS active, pending, under-contract, and coming-soon listings as of October 5, 2026, matched to Worcester County property records published by the Maryland State Department of Assessments and Taxation through Maryland's open data portal, last updated September 3, 2026. 516 of 691 listings matched, 75 percent. The base is 31,423 residential parcels in ZIP code 21842 with a street address and a recorded deed date. Listing rate is the share of each cohort's parcels currently on the market. Overall rate, all cohorts: 1.6 percent.
Based on information from Bright MLS for the period September 1, 2026 through October 5, 2026.
Properties held one to five years are listing at about 2.0 percent of their cohort. Properties held ten years or more are listing at about 1.4 percent. That is the same difference of roughly one and a half times that we reported in August. The median property on the market has been held 6.4 years by its current owner, against 7.7 years for the market as a whole.
Broken out by year of purchase, properties deeded in 2022 through 2024 are listing at 2.2 to 2.5 percent, the highest of any three consecutive purchase years. Properties deeded in 2020, at the start of the pandemic-era buying, are listing at 1.4 percent, below the market average.
The same pattern shows up in what closed. Of the September sales we could match, the median seller had held the property 5.8 years, and 42 percent had owned it for less than five years.
What the table cannot tell you is why any individual owner is selling, and this report does not guess. What it does tell a buyer is that a meaningful share of what is on the market was bought within the last five years, and the last sale price is a matter of public record.
A note on method: the deed date is the last recorded transfer for each parcel, which includes transfers into trusts and between family members as well as arm's-length purchases, so a small share of "recent" deeds are not recent purchases. The county records were last updated September 3, 2026, so a property that changed hands in September still shows its previous deed. Listings with Berlin mailing addresses in the West Ocean City MLS area fall outside the 21842 ZIP code and are not matched. Parcels without a street address, mostly vacant lots and common areas, are excluded from the base.
What This Means For Buyers Right Now
If you are buying in Ocean City or West Ocean City right now, September gave you something August did not: room to negotiate on the right listings.
Nearly half of all active listings are priced below their original asking price, and about three in four of the listings that have been on the market more than three months have already been cut. Those owners listed in the spring with a number in mind, and the end of the season has changed their thinking. Inventory is at about six months of supply, the median property takes two months to sell, and fewer buyers are here in October than in July. That is leverage, and it is reasonable to use it.
It is not a reason to overreach. The listings that were priced right from the start are still selling in days, sometimes above asking, and Direct Oceanfront condos sold in a median of 18 days in September. A buyer who offers far below a correctly priced listing will lose it to the next buyer. As Grant puts it in his Market Minute, get the best deal you can, and if it is the right property, buy it.
If I were buying today, I would look first at the listings that have been on the market more than 90 days and have already been reduced, because those owners have shown they are ready to talk. I would look hard at Bayside Waterfront, where sales took a median of 103 days in September and half of the active listings are below their original ask. And I would move quickly on anything correctly priced on the oceanfront, because that is the segment where the leverage is thinnest.
Deciding whether the timing is right for you is its own question, and our take on whether buying here makes financial sense is a good place to start.
What This Means For Sellers Right Now
For sellers, September's message is that the market is pricing your competition down around you.
If you listed in the spring and have not had an offer, you are in the largest group on the market, and most of the owners in that group have already reduced. A buyer comparing your listing to the one next door is looking at a price that has probably come down by about 5 percent from where it started. The reductions are reaching the closing table: the reduced listings that sold in September had come down a typical 6.4 percent from their original asking prices before they sold, the deepest typical cut in our data.
The other side of that message is encouraging. Correctly priced properties are still selling quickly. Twenty-nine percent of September's sales closed at or above asking, the oceanfront sold in a median of 18 days, and a $3.9 million waterfront home sold at its full asking price without a single reduction. Buyers are still paying full price for properties priced to the market. What they are declining to pay is spring pricing on properties that did not sell in the spring.
If I were selling today, I would price against September's closed sales in my sub-market and against the reduced prices of my direct competition, not against the original asking prices I see on similar listings. I would expect a slower fall and winter than the summer, and plan for it rather than wait for spring to rescue a high price. And if I had been on the market since the spring, I would adjust to the market now rather than chase it down through the winter.
A current valuation, a look at how to prepare a condo for sale, and an honest review of the most common seller mistakes are the right starting points.
What This Means For Investors Right Now
For investors, September is about price discipline on the buying side and patience on the selling side.
The twelve-month median is up 3.5 percent and the condominium twelve-month median is up 4.8 percent, so values are still rising slowly. What changed is the negotiating environment. With nearly half of active listings below their original ask, an investor buying this fall can set a price based on what the numbers support rather than what the seller first hoped for. The core $250,000 to $600,000 band still holds more than half of all sales, and that remains the part of the market where rental logic, price, and resale path most reliably line up.
The tenure data adds a practical point. A meaningful share of what is listed was bought between 2022 and 2024, which means the current owner's purchase price is recent, public, and a reasonable anchor for what they hope to net. That is useful information in a negotiation.
If I were evaluating an Ocean City investment property today, I would be less interested in whether September's median fell and more interested in whether the building, location, fee structure, rental demand, and resale path make sense together at a price set by September's closed sales in that sub-market. Financing investors should expect condo documents, fees, special assessments, building financing eligibility, rental rules, insurance, and realistic income assumptions to matter as much this fall as they did all year.
Frequently Asked Questions
Did The Ocean City Real Estate Market Slow Down In September 2026?
Yes, in pace but not in price. Closed sales fell to a preliminary 84 from 102 in August and 120 in September 2025, median days on market rose to 57, and active inventory reached about 6.2 months of supply. At the same time, the twelve-month median rose to $460,500 through September 30, 2026, up 3.5 percent year over year, and the September median of $482,500 was 9.9 percent above September 2025.
Are Ocean City Sellers Cutting Prices?
Yes. Of the 398 listings that were on the market from September 3 to October 5, 2026, 103, about one in four, cut their asking price during September, typically by about 3 percent. Of all 559 active listings on October 5, 2026, 265, or 47 percent, were priced below their original asking price. Listings on the market more than 90 days were the most likely to have been reduced, at about three in four.
Are Ocean City Condo Prices Going Up?
Slowly. Counting only properties recorded in Bright MLS as condominium ownership, the twelve-month median through September 30, 2026 was $440,000 on 767 sales, against $420,000 on 832 sales in the prior twelve months, up 4.8 percent. The September condominium median was $461,000 on 53 sales. Monthly figures move with the mix of what sold; the twelve-month figure is the better guide.
Is Ocean City Currently A Buyer's Market Or Seller's Market?
It is at the edge of balanced, with buyers holding a little more leverage than in the summer. Active inventory stood at 559 listings as of October 5, 2026, about 6.2 months of supply on the trailing three-month sales pace, and nearly half of active listings are priced below their original ask. Correctly priced properties still sell quickly, though: 29 percent of September sales closed at or above asking, and Direct Oceanfront sales took a median of 18 days.
Why Did August's Sales Figure Not Change?
The August report called its 102 sales preliminary because Bright MLS settlements are often reported on a lag, and earlier in 2026 that lag was large: May was first reported at 117 sales and finished at 130. In August's case, no late settlements were recorded, and the month finished at 102. July rose by one sale after its first report. September's 84 is preliminary on the same basis, and recent months suggest any revision will be small.
Which Ocean City Sub-Market Was Strongest In September?
Bayside Waterfront by volume, with 25 sales at a $525,000 median, its fourth consecutive month leading the market, and six of the month's nine sales at $1 million or more. Direct Oceanfront by speed and by price per square foot, with a median of 18 days on market and $577 per square foot.
How Long Are Ocean City Properties Taking To Sell?
The median property took 57 days in September 2026, up from 48 in August and 37 in September 2025. The range by segment was wide: Direct Oceanfront properties sold in a median of 18 days, while Bayside Waterfront properties took a median of 103.
Who Is Selling In Ocean City Right Now?
Disproportionately, the owners of properties deeded within the last five years. Matching current listings to Worcester County property records shows properties held one to five years listing at about 2.0 percent of their cohort, against about 1.4 percent for properties held ten years or more. Properties deeded in 2022 through 2024 are listing at the highest rates of any three consecutive purchase years, 2.2 to 2.5 percent. The median property on the market has been held 6.4 years, against 7.7 years for the market as a whole.
Why Do Your Market Reports Sometimes Differ From National Real Estate Websites?
National websites often rely on broad automated datasets, countywide figures, estimated values, or delayed public records. This report is based on closed Bright MLS sales in specific Ocean City and West Ocean City MLS areas, paired with firsthand interpretation from active local agents. That difference matters because Ocean City is a resort market with many micro-markets that can each behave differently in the same month.
Three Things I'll Be Watching In October
Every monthly report answers one set of questions and creates another. Heading into October, three stand out.
The first is whether the price cuts turn into sales. There are 178 active listings that have been on the market 91 to 220 days, and seven in ten of them have already been reduced. If October's closed sales include a large share of long-listed properties at deep discounts from their original asking prices, the adjustment is working. If the share of active listings below their original ask climbs well past half while closings fall, the gap between sellers and buyers is wider than September suggests.
The second is inventory. At 559 active listings and about six months of supply, the market is at the edge of balanced. If active listings fall back toward 500 by early November, September and early October were the seasonal high point. If they climb past 600, buyers will carry more leverage into the winter.
The third is whether November and December repeat 2025. Grant expects a more traditional, slower winter this time. In November and December 2025, 208 sales closed, the same pace as the rest of that year, with 21 at $1 million or more. The pending count at the start of November will be the first sign of which way this winter goes.
Grant's Market Compass
A quick read on what strengthened, held steady, and softened in September.
Strengthening: The twelve-month median and twelve-month price per square foot, Direct Oceanfront absorption speed, the two-bedroom twelve-month median, and buyer leverage on listings that have been on the market since the spring.
Holding Steady: Seven-figure activity, the core price band between $250,000 and $600,000, the share of sales above $600,000, contract signings against September 2025, the pending pipeline, and the list-to-sale ratio.
Softening: The closed sales count, median days on market, months of supply, Bayside Waterfront speed, cash participation at the top of the market, and asking prices on listings that have sat since the spring.
The compass is pointing toward a market returning to a normal fall. Values are still rising slowly over twelve months; the pace and the pricing power have shifted, for now, toward buyers who are patient and sellers who are realistic.
Market Outlook
Heading into the winter, the Ocean City real estate market is doing what Grant expected it to do: slowing down, sorting itself out, and giving buyers a little more room than they had in the summer.
The headline data describes a slower month. The twelve-month trend, the price per square foot, and the speed of correctly priced sales describe a market whose values are intact. The listing data describes owners who priced for the spring and are now meeting the fall. All three are true at once, and none of them calls for panic on either side of the table.
What I am reasonably confident about is this: the middle of the market is stable and appreciating slowly, the oceanfront priced to the market is selling fast, and the owners who listed high in the spring are adjusting. Buyers who find the right property this fall should expect to negotiate, and the sellers who price to September's sales rather than April's hopes are the ones selling.
What I am not yet confident about is the winter. Inventory at six months of supply and a median of 57 days on market leave room for the season to go either way. Whether November and December look like 2025's surprisingly strong ones or like the quieter winters this market used to have is the question the next two reports will answer.
Why You Can Trust This Report
Unlike reports that rely solely on automated national datasets, this one combines Bright MLS sales data with active market participation: buyer and seller consultations, showing activity, inventory analysis, contract activity, pricing conversations, and nearly three decades of firsthand Ocean City real estate experience.
It also means being willing to say when the data did not do what we expected. The August report called its 102 sales preliminary and expected them to rise as late settlements came in. None did, and this report says so. September's count is preliminary on the same basis, and the year-over-year comparison should be read accordingly.
The goal is simple: help buyers, sellers, investors, and owners understand what is actually happening in the Ocean City real estate market, without sensational headlines or overly broad national assumptions.
Ocean City is a resort market, a condo market, an investment market, a second-home market, and a lifestyle market all at once, and those layers matter. Reading the numbers correctly requires more than pulling statistics from a database. It requires understanding how buyers think, how sellers respond, how buildings differ, and how individual micro-markets behave from one month to the next.
As Joan Y. put it after selling a property with Grant:
"...He was very responsive to our call(s) and on the first visit was extensively prepared with comparable properties (recently sold and currently on the market). His knowledge of the OCM market, property values, experience and facts helped address our pricing issues."
About The Author
Grant Fritschle is a second-generation Ocean City Realtor and co-founder of The Fritschle Barker Group at Keller Williams Realty of Delmarva. With 29 years of experience and more than 2,000 personal transactions, Grant specializes in oceanfront condominiums, waterfront homes, investment properties, vacation homes, luxury real estate, and resort market analysis. Jon Barker brings more than 20 years of his own experience to the team.
Grant is also co-owner of Central Reservations, one of Ocean City's largest vacation rental management companies, a financial interest disclosed here for transparency, and one that gives him a rare view of both property ownership and rental performance.
Data Source: Bright MLS. Statistics reflect closed sales reported through September 30, 2026 for Ocean City and West Ocean City MLS areas 80 through 85, over $50,000, all property types except timeshares. Two September sales whose price covers more than one property are excluded from every figure. September figures are preliminary and may be revised as additional sales are reported. August 2026 figures are unchanged from those published in the August report. Rolling twelve-month figures cover October 1, 2025 through September 30, 2026, compared against October 1, 2024 through September 30, 2025. Inventory, pending, under-contract, and coming-soon counts are as of October 5, 2026. Price changes compare Bright MLS records pulled September 3, 2026 and October 5, 2026. Ownership tenure figures are derived from Worcester County property records published by the Maryland State Department of Assessments and Taxation, last updated September 3, 2026, matched to listings by property address. Based on information from Bright MLS for the period April 6, 2023 through October 5, 2026.
Trust Source Disclosure: This report was researched, written, reviewed, and interpreted by real members of The Fritschle Barker Group. Artificial intelligence tools may be used for editing, formatting, and readability. All market analysis, observations, and opinions reflect local expertise, MLS data, and firsthand experience serving Ocean City and Delaware beach real estate clients.
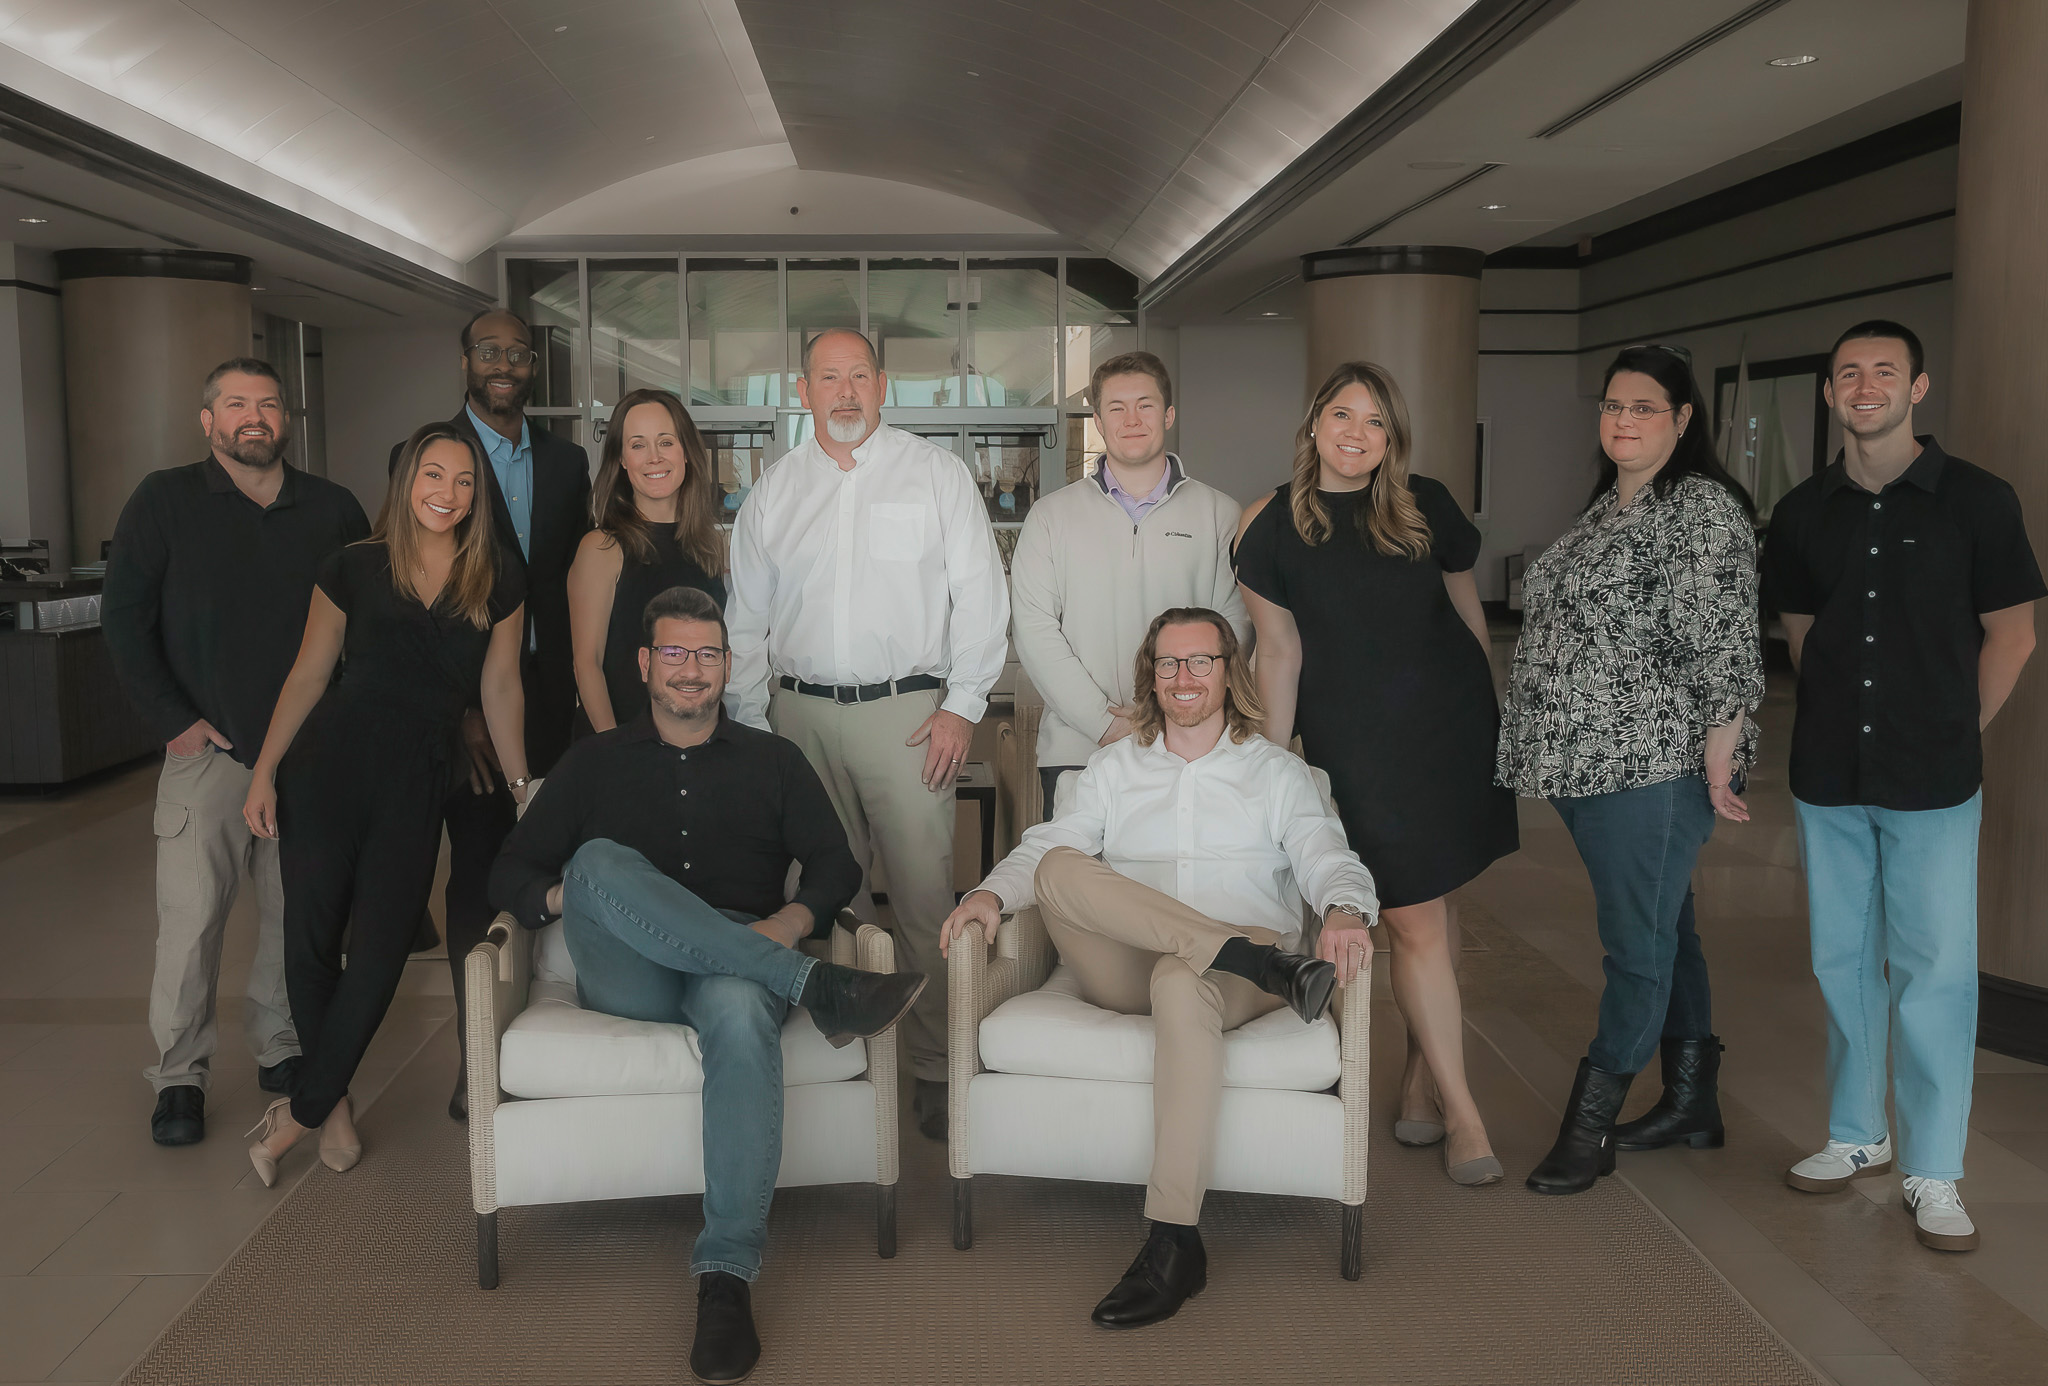
Your Top Ocean City, MD Real Estate Agents
Today, they are recognized nationally as a top-performing group of charismatic, skilled Agents deeply connected to the vibrant towns of the Eastern Shore. More than agents, they are trusted advisors and community advocates, blending local knowledge with national strategy to deliver exceptional results.
The Fritschle Barker Group at Keller Williams Realty of Delmarva adheres to all Fair Housing Act guidelines and NAR ethical standards.